

By Paul Mueller, American Institute For Economic Research
President Trump’s conflicts with Chairman Powell and with Governor Cook have obscured real shortcomings at the Federal Reserve and brought little useful change. These conflicts tend to focus on whether the Fed’s target interest rate is too high or too low. Meanwhile, institutional problems at the Fed have been largely overlooked.
But there is an opportunity here with Trump’s nominee for Fed chair, Kevin Warsh. His first task will be navigating a hostile Senate. But should he be confirmed, Warsh’s time would be best spent cleaning up the Federal Reserve system: its personnel, spending, and data.
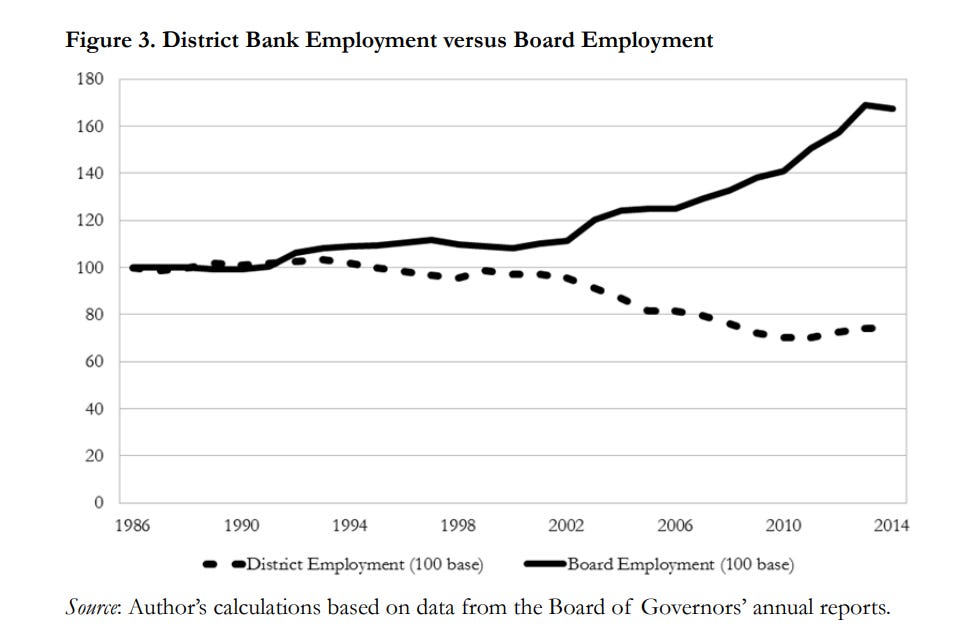
The Federal Reserve System employs 24,000 people. The Board of Governors has about 3,000 employees, while the 12 district banks employ the remaining 21,000. That figure includes 800–1,000 professional economists. While the Fed has recently announced plans to reduce its workforce by 10 percent, that would still leave it with over 21,000 employees. But why shouldn’t the Fed cut headcount by 20–30 percent, or even more?
Does the Fed really need that many employees? After all, this isn’t the 1960s or 1970s when many things had to be done by hand. Not only have there been significant technological improvements and greater automation over the past fifty years, the development of AI will also accelerate this trend. As such, the new Fed chair should reevaluate whether the Fed needs so many employees.
Besides being wasteful, the high number of economists employed by the Fed has likely influenced the profession to unduly favor the status quo. Those who criticize the Fed or question whether it should even exist find themselves in the wilderness of monetary economics. Employing fewer economists will reduce the Federal Reserve’s gravitational pull on the economics profession.
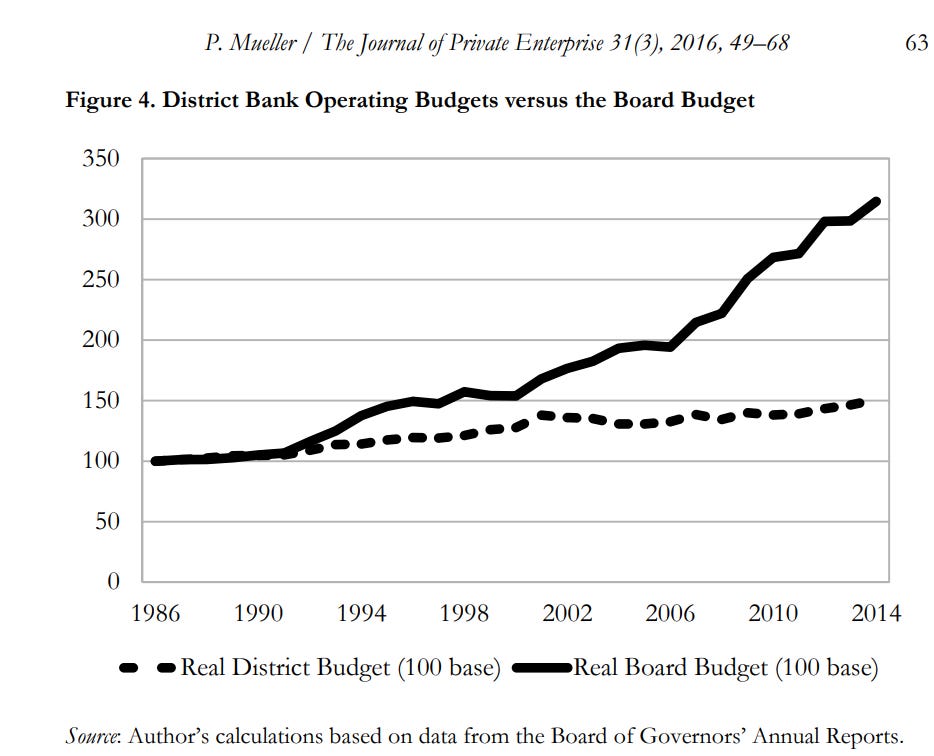
Along with reducing headcount through reorganization and consolidation, the Federal Reserve is ripe for an audit of its spending. Ron Paul popularized the idea of auditing the Fed in 2008. The Federal Reserve is unique in that it can literally create money and in that it sets its budget independent of Congress. What would you expect the budget trend to be for a fully self-funding organization that can print money? If you said up and to the right, collect your prize.
The budget of the Board of Governors of the Fed has grown more consistently than the Federal budget for decades. In fact, why would any office or department at the Fed ever voluntarily reduce its spending? As such, we don’t see examples of significant retrenchment or budget cuts across the Board of Governors. District banks, on the other hand, operate with private-sector participation through their member-bank stockholders, yet they still suffer from bureaucratic bloat due to limited market competition.
By restructuring staff, streamlining operations, and auditing its spending, the new Fed chair can couch all of this change in terms of modernizing the institution. The Fed has largely failed to keep abreast of technological change when it comes to data, metrics, and execution. It still relies heavily on surveys and anecdotal conversations when it has access to millions of data points, nearly in real-time.
Consider the following key indicators that the Fed officials rely on:
They measure their key inflation target using the Personal Consumption Expenditures (PCE) price index, as well as the Consumer Price Index (CPI) and the Producer Price Index (PPI). Yet these numbers only come out once a month. Rather than calling on business leaders to get a read on economic conditions, they could use real-time measures from sources like the Adobe Digital Price Index or Truflation that use millions of transactions to assess economic activity.
Similarly, most of the key indicators the Fed uses for assessing the strength of the labor market (the unemployment rate, nonfarm payrolls, labor force participation rate, and various measures of underemployment) tend to be released monthly as well.
The important measure of economic growth, the Gross Domestic Product (GDP), only comes out quarterly—though there are frequent estimates. Furthermore, the measures of GDP tend to be revised often, too. The Atlanta Fed produces a “GDPNow” number—but it also relies primarily on estimates rather than real-time data. Indicators like industrial production, retail sales, and business investment are not much better.
One area the Fed does make use of real-time data is in financial market conditions. Interest rates (e.g., federal funds rate, Treasury yields), credit spreads, and asset prices change in real-time and can be used to assess financial stability and the effectiveness of monetary policy.
In addition to the delays, most of these core metrics, particularly GDP and the unemployment rate, are lagging indicators. They reflect past economic performance rather than providing real-time insights into current or future trends. In a rapidly evolving global economy, relying heavily on backward-looking data can lead to policy decisions that address emerging challenges too slowly or exacerbate existing ones.
The FOMC’s framework often emphasizes aggregate demand management, assuming that inflation is primarily a demand-side phenomenon. But recent economic shocks (supply chain disruptions, energy price spikes) highlight the critical role of supply-side factors. Over-reliance on demand-side metrics can lead to inappropriate policy responses.
In fact, many economists argue that the Fed should be less reactive in general. Friedman noted that there were “long and variable lags” between the implementation of monetary policy and its effects. Following predictable monetary rules will likely generate more stability and more growth in the long run.
Monetary policy (in terms of target interest rates) matters, but so does operational efficiency, utilization of technology, and access to good information. Institutional reform may also help the Fed rebuild public trust by reassuring people that its decisions reflect reality today rather than reality months ago – or not at all. Cleaning up the Federal Reserve will be a monumental task, but it will also be a legacy. Let’s hope Mr. Warsh is up for the challenge.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions. All positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
Downsizing is the essential first step to elimination. The FED is not Constitutional. It isn’t even competent. Moreover, it is not accountable. This is a bank run by interested bankers in service to bankers. It is a money laundering organization for debt notes. It transfers the cost of risky business practices to innocent civilians. It facilitates unmanageable and unpayable debt that crushes hard-working Americans. It is flat evil.
As almost always, QTR hits another one out of the park. I enjoy essays that analyze an old problem from a new perspective, in this case, downsizing a Federal agency. Adjusting the Fed Rate and deciding upon monetary policy is interesting, but the mechanics of government and global ramifications of policy are more so.