

By William J. Luther, AIER’s Daily Economy
Many market watchers are concerned about the softening labor market. According to the Bureau of Labor Statistics, the US economy lost 92,000 nonfarm payroll jobs in February 2026. The revised payroll numbers reveal that the economy added just 156,000 jobs over the last year — or, roughly 13,000 jobs per month. That certainly looks sluggish relative to earlier reports. For comparison, the economy added roughly 122,000 jobs per month in 2024 and 210,000 jobs per month in 2023.
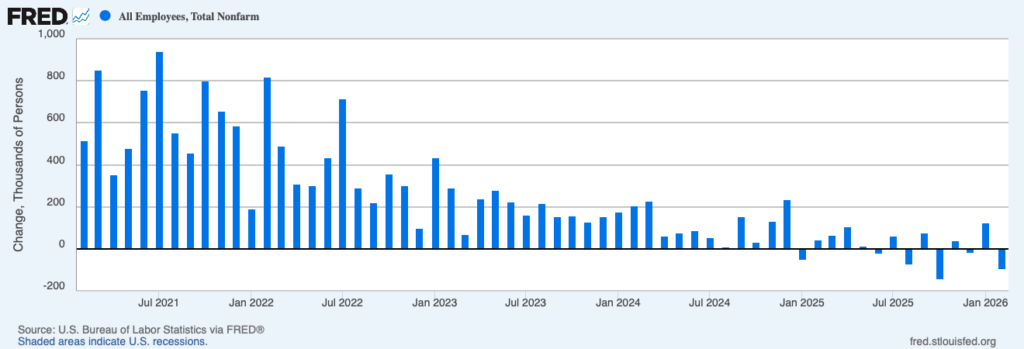
Some market watchers suggest the labor market looks even worse when you disaggregate the data. As economist Justin Wolfers notes, just one sector “continues to account for more than all of the jobs created over the past year.” Whereas health care and social assistance has grown 3.2 percent since the beginning of 2025, employment across all other sectors has declined 1.2 percent. That, the pessimists say, looks like concentrated job growth masking general malaise.
To the extent that those currently concerned by the most recent labor market data are merely looking for the proverbial canary in the coal mine, it is hard to fault them. It is difficult to identify turning points in real time, and it is prudent to consider whether what one is observing might indicate that the labor market is starting to soften. But the view that the labor market might be starting to soften is often conflated with a very different view: that the labor market is soft. And that latter view, at least at the moment, is inconsistent with the available data.
Zoom Out
Slow job growth is not necessarily a sign of a soft labor market. An economy at or near full employment will also experience slow job growth. And, when we zoom out on the labor market data, it certainly looks like we are at or near full employment, where everyone who wants a job at the prevailing wage has a job and unemployment reflects normal frictions associated with moving from one job to another.
Consider the prime-age employment-to-population ratio, which shows the share of people in the US between the ages of 25 and 54 who are currently employed and, correspondingly, tends to be a good indicator of labor market strength. In February 2026, 80.7 percent of prime-age workers were employed. That’s relatively high by historical standards.
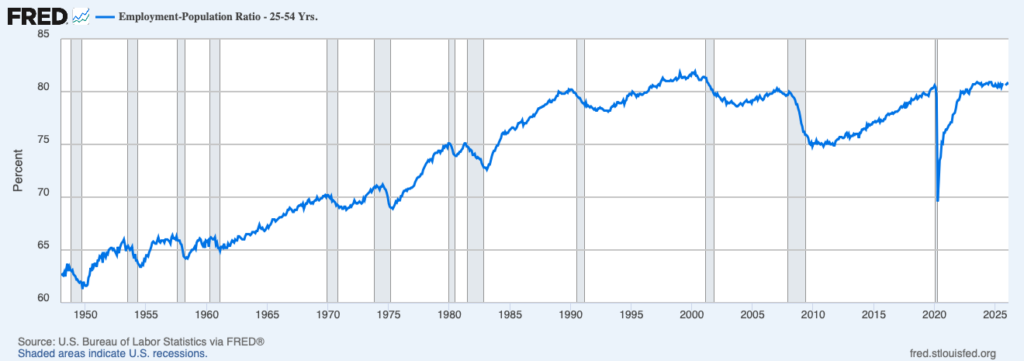
The prime-age employment-to-population ratio climbed from 62.6 percent in 1948 to 80.2 percent in 1990, as women gradually entered the formal labor market. Since then, a prime-age employment-to-population ratio above 80.0 percent has generally indicated a relatively strong labor market, whereas a ratio that drops below that threshold typically indicates labor market weakness. The full series peaked at 81.9 percent in April 2000. Local peaks at 80.2 percent in March 2007 and 80.6 percent in January 2020 preceded recessions, but the series has been much more stable in recent years. The prime-age employment-to-population ratio has exceeded 80.0 percent since December 2022.
Reasonable people might disagree about the precise prime-age employment-to-population ratio that is consistent with full employment at any given point in time. And that ratio will change as families determine whether it is more advantageous to have dual earners or to have one member specializing in home production. But it is not obvious that family structure or other potential factors affecting the ratio consistent with full employment have meaningfully changed over the last six years. And no one thought the labor market was soft in January 2020.
Factors Affecting Job Growth
If the economy is below full employment and recovering, it will tend to add a high number of jobs each month. If it is at or near full employment and the population of working-age adults is growing rapidly, it will tend to add a high number of jobs each month. But neither of those conditions appear to hold at the moment. The prime-age employment-to-population ratio suggests the economy is at or near full employment. And, at the same time, broader demographic trends and more recent immigration enforcement efforts have contributed to slow growth in the population of working-age adults. Consequently, slow job growth should be expected.
Furthermore, if average job growth will tend to be slow when the economy is at or near full employment, then negative job growth will be more likely in any given month. The logic is straightforward. Above-average job growth in one month implies below-average job growth in some other month. The closer average job growth is to zero, the more likely below-average job growth means negative job growth.
Much the same can be said with respect to the high concentration of jobs in a single sector. If average job growth is zero, additional health care and social assistance jobs necessarily imply job losses in other sectors. With low (but positive) average job growth, some additional health care and social assistance jobs can be created without reducing jobs in other sectors. But there’s a limit. And, at least at present, it appears that our aging population requires some sectoral rebalancing of jobs.
Productive Job Losses
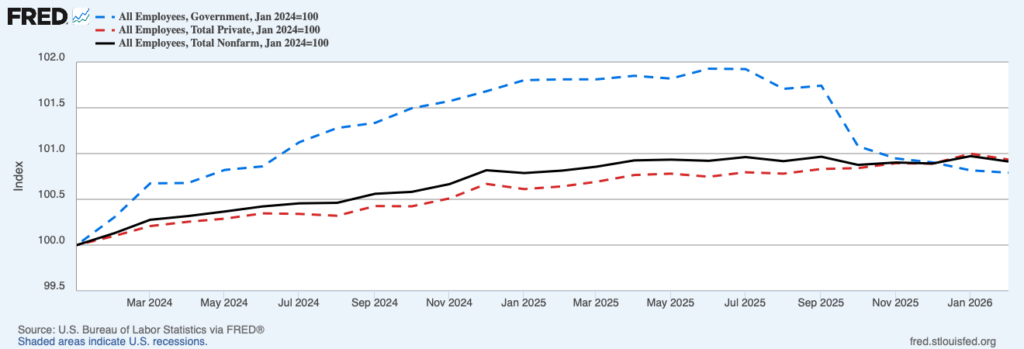
It is tempting to think that job gains are good and job losses are bad. But, of course, reality is much more complicated than that. Indeed, at least some of the job losses over the last year appear to be productivity-enhancing. In particular, the last year has seen a major reduction in government jobs, freeing up additional labor for the more-productive private sector.
From January 2024 to January 2025, the last year of the Biden administration, government employment increased 1.8 percent compared with just 0.6 percent growth in private employment. That excess government job growth has been largely undone by the Trump administration. In February 2026, government employment was just 0.8 percent higher than it had been in January 2024, whereas private employment was 0.9 percent higher.
The Labor Market Remains Near Full Employment
It is easy to understand why many market watchers are concerned by the latest employment data. They worry that slow job growth will become no job growth, and that no job growth will become negative job growth. But we must recognize the difference between what might happen and what has happened. At the moment, the economy appears to be at or near full employment, where slow job growth is the norm.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions. All positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
Keep in mind Federal government employment soared to over 3 million during the Autopen's presidency. Trump is unwinding this. His presidency is also causing the unwinding of employment in NGOs, corporate media, Hollywood and HR departments. So a softening in the labor market is to be expected.
On the other hand, job openings for Americans increased when Trump paid illegals to self-deport. But that program has slowed to a halt. So Trump could help himself immensely by not limiting deportations to criminals. Deporting rapists, scammers and murders do not open up jobs for US citizens. ICE sweeps through factories, meat packers, construction sites, landscaping routes, Home Depot parking lots and H-1B fraudsters would have a two-fold impact - relieving stress on the social safety net and opening up "on-the-books" jobs for American citizens.
In summary, the clean-up of the mess created by Biden is, by necessity, going to be ugly. And so are future job reports as the numbers normalize under a health economy not burdened by intentional Marxist destruction.
I still think we need to dig deeper to understand if some of the drag could be due to immigration enforcement. We know Transportation labor is being reset (hopefully).
That begs the question: What happens if you remove millions of consumers from the economy? I remember Ronnie's Amnesty. I can't believe we're here.