

One of the more embarrassing habits of modern finance is its insistence on pretending the stock market has some integrity left.
Capital, we used to think, flowed to the most productive businesses. Prices reflected fundamentals. Risk was priced. The market, in the long run, separated signal from noise and rewarded cash generation over fantasy. That is the civics-class version of markets, and at this point it bears no resemblance to the one we actually trade in.
The market’s core failure right now is not simply overvaluation. Markets have always produced overvalued stocks. The deeper problem is that speculative inflation can now be mechanically converted into benchmark legitimacy and then forcibly distributed to passive investors as “diversification.”
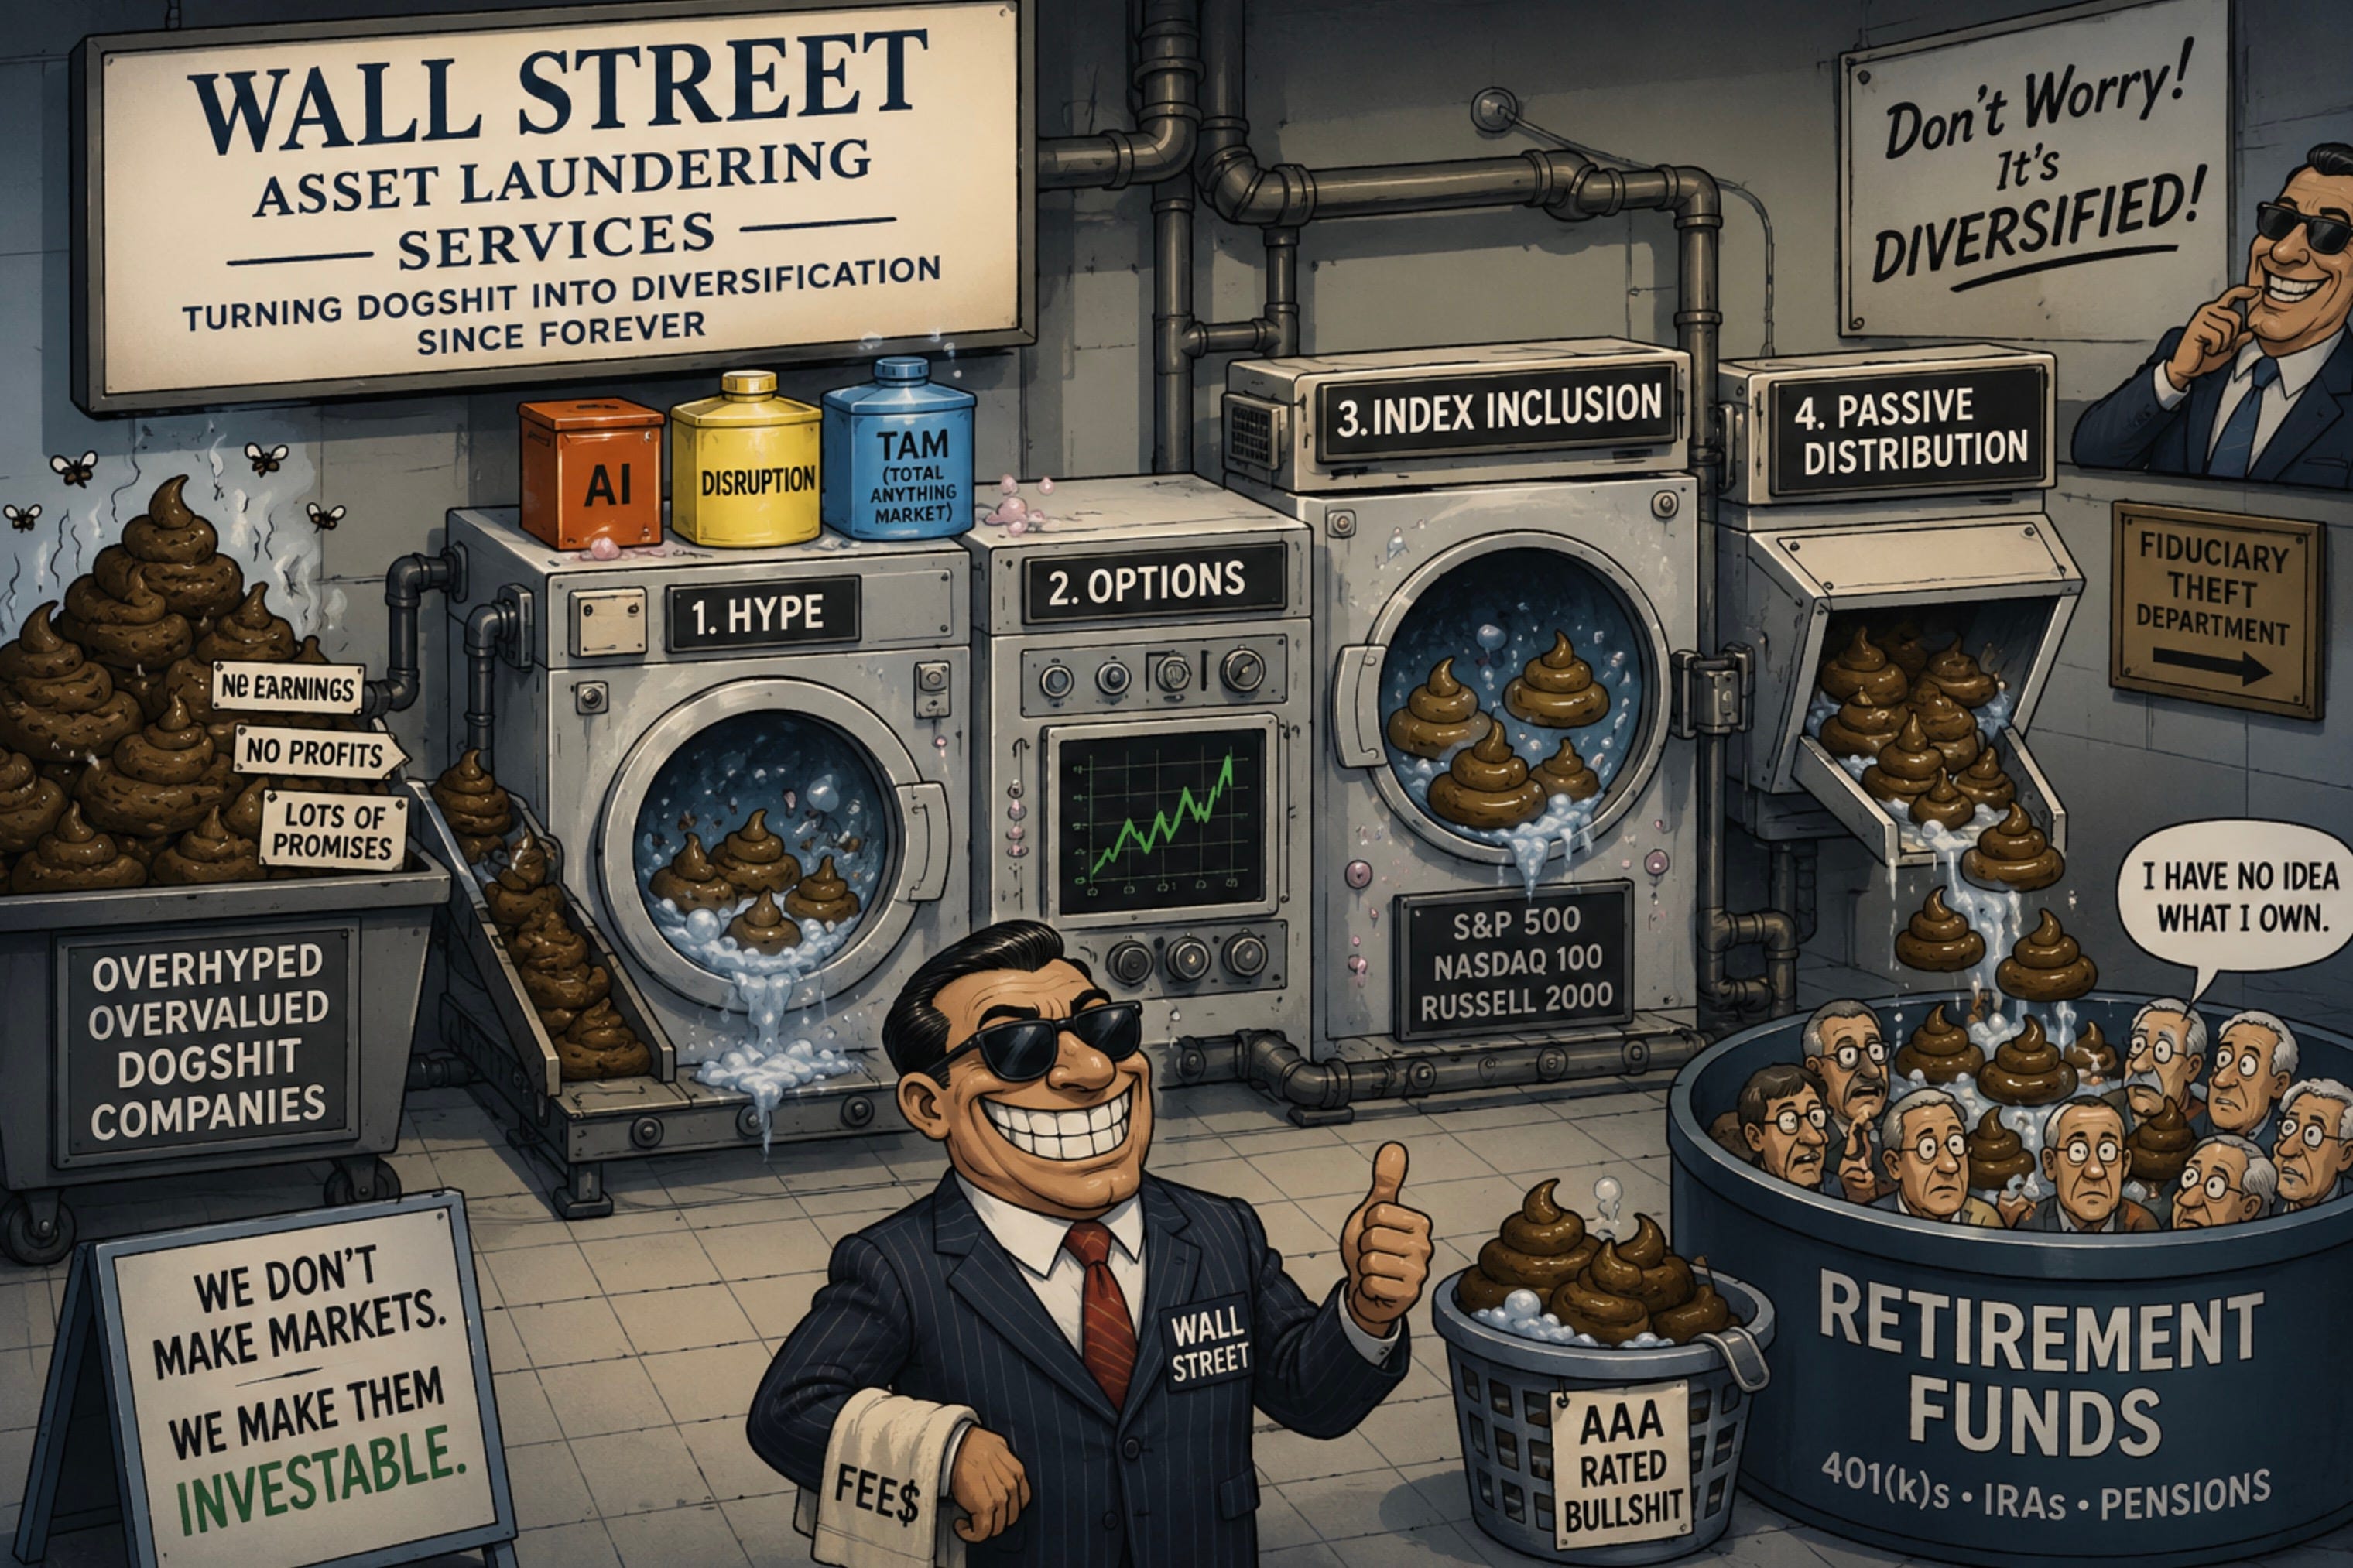
In other words, the modern market increasingly allows stocks to get bid up through narrative, call option activity and momentum, then ratifies those bloated valuations through index inclusion, and finally pipes them directly into the retirement system through ETFs, mutual funds and model portfolios.
This is why we see ridiculous things like companies with negative earnings outperforming companies with positive earnings. “Something is broken in price discovery…” wrote Apollo’s Chief Economist about this chart last week:
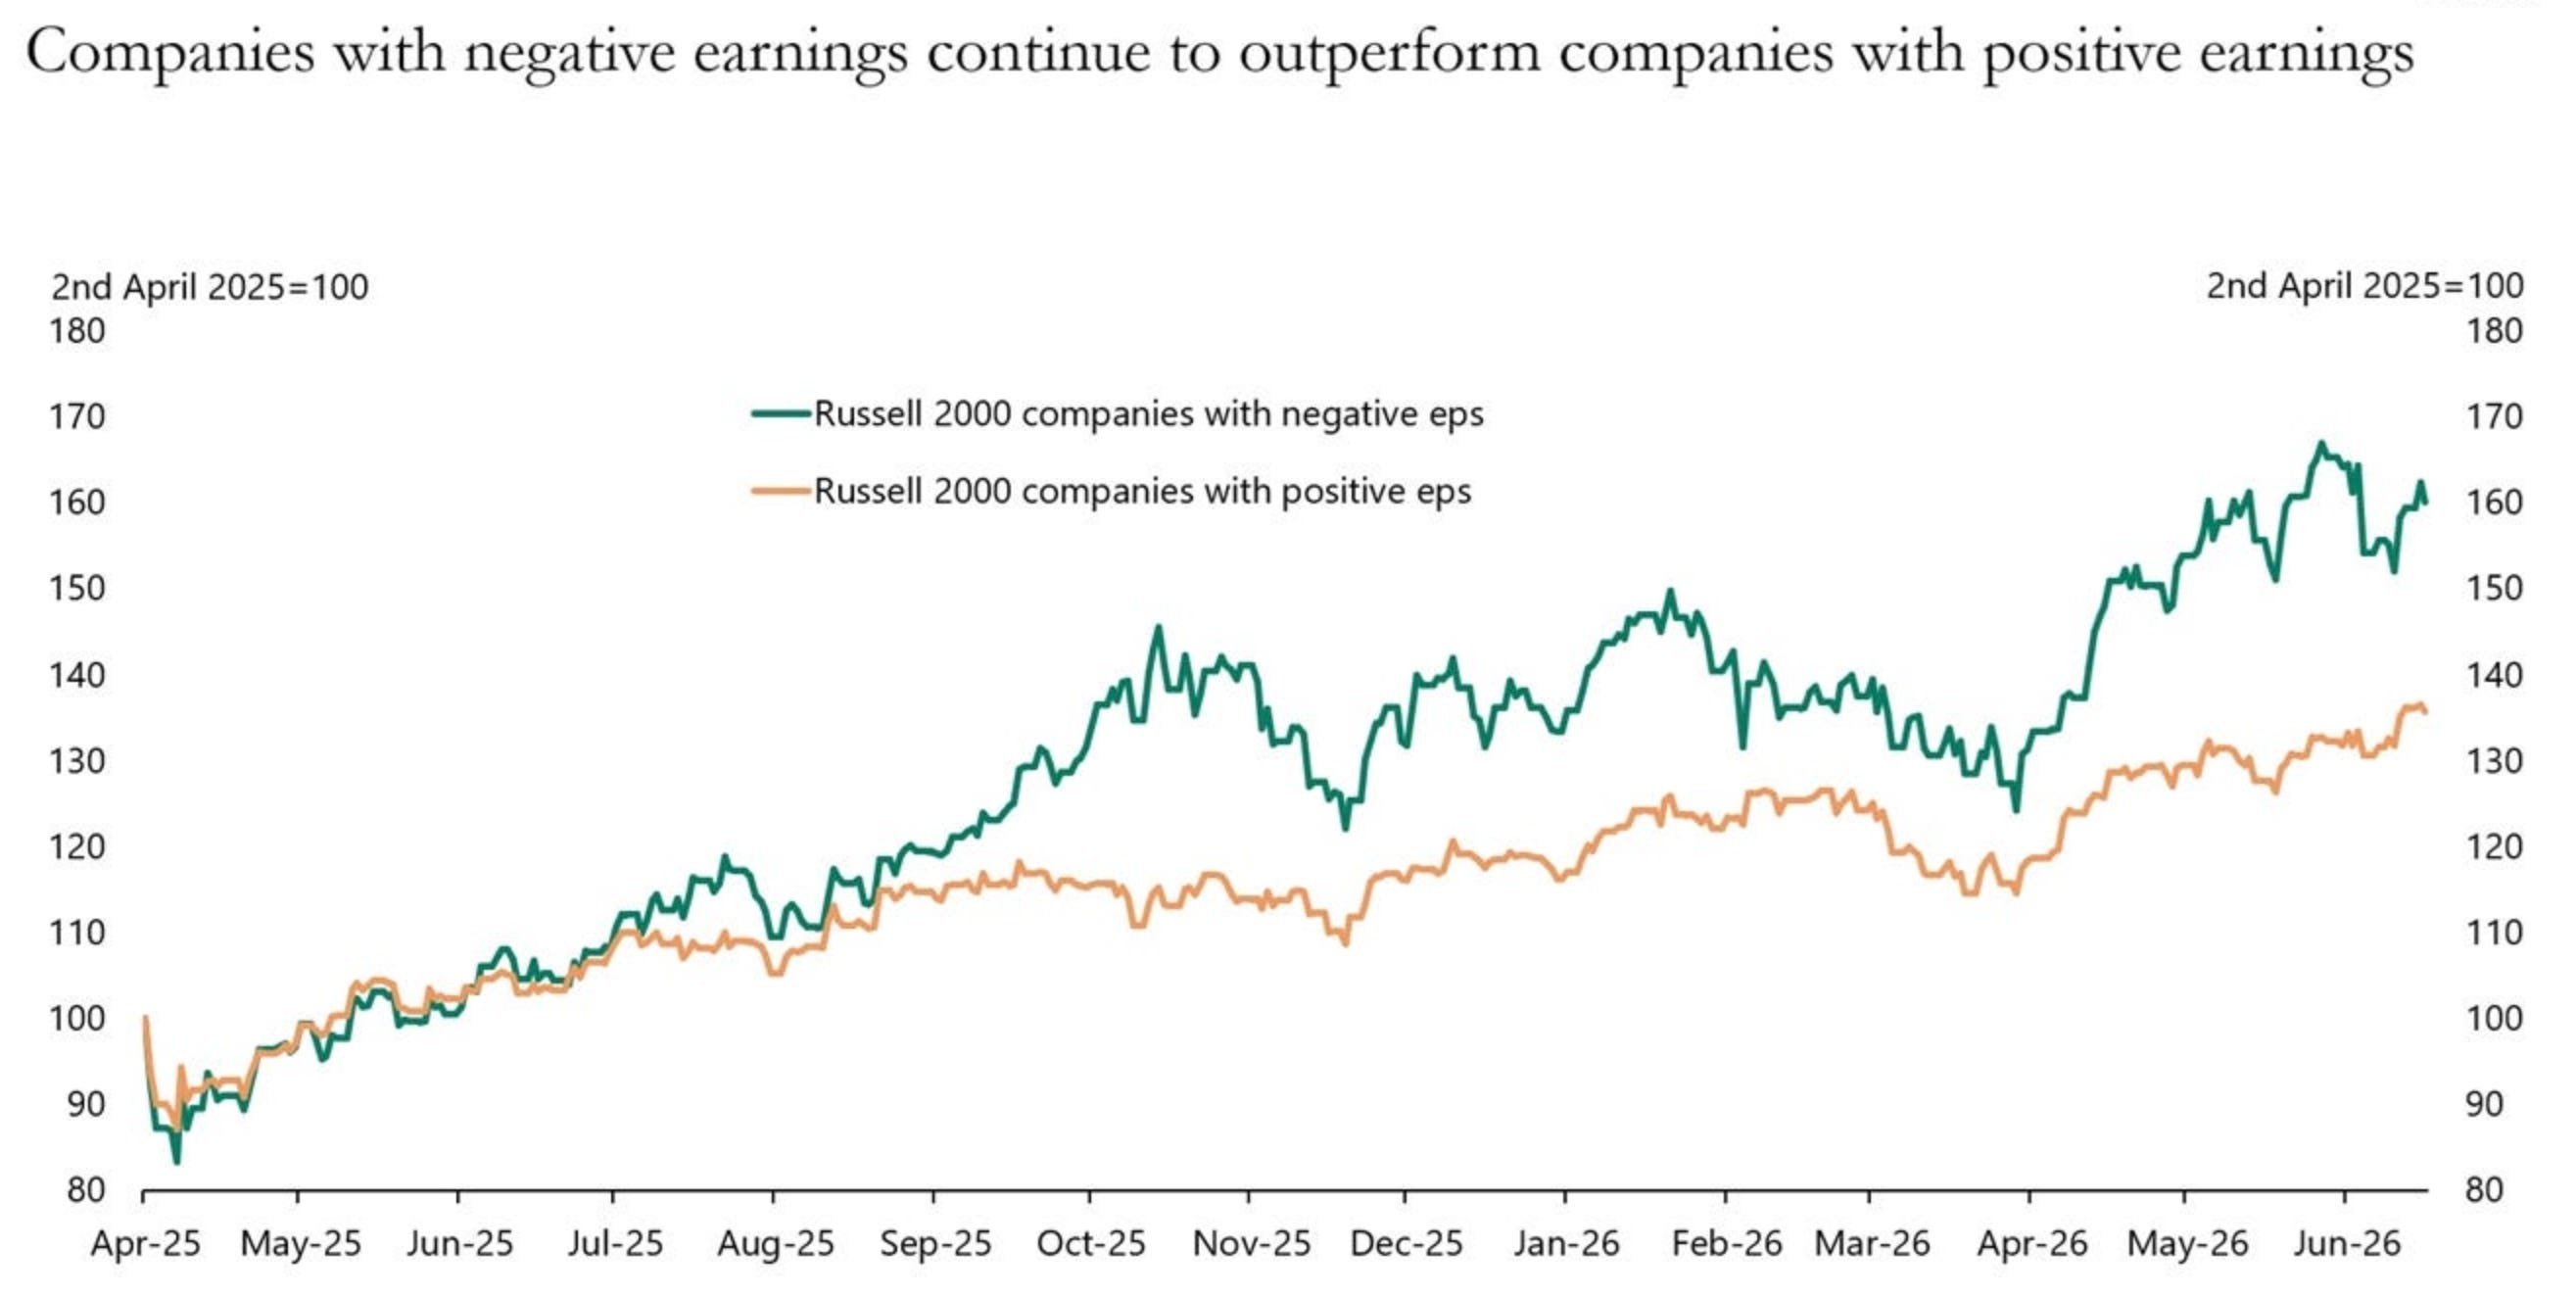
He’s right. It’s not price discovery. It is a structural conveyor belt for institutionalizing air pockets and gutting the once conservative retirement and pension accounts millions of Americans depend on to be there for them in due time.