

As I’ve said before, my friend Mark Spiegel sometimes feels like the last living value investor in history.
I love talking to Mark because, in his mind, our markets and the laws of economics haven’t been coopted and usurped by the insanity of Modern Monetary Theory and money printing yet. Well, Mark understands those concepts drive markets nowadays, he has just not given in to the idea that they will forever.
In other words, Mark believes that markets will again revert back to historical averages and normalcy at some point. And while his fund has had a difficult run the last year or two, Mark has started 2026 beating the S&P 500 by a couple percentage points.
My main thesis for being bullish heading into 2026, as I see it, is simply: the rules don’t apply anymore and everything is broken, so the market will never again trade on historical fundamentals or with any semblance of sanity ever again.
So far, this is the case that has been winning out in markets over the last few years, thanks to caustic monetary policy and an unsophisticated retail investor base, layered on top of a passive bid that doesn’t care about P/E ratios or the like.
That’s why I value Mark’s perspective. It’s a view of markets I see less and less as I drift toward the idea that, because of QE, maybe we never revert to the mean. Mark is the counterbalance to that thinking. And deep down, I’m still a fundamental investor—far more so than many market participants today.
Mark’s March letter is out, and in it he continues to explain why he believes the market is overvalued. He says he’ll be short again soon, but isn’t yet. This letter is dated March 31, 2026 and includes five of his long positions, including 3 with dividends at or near 6%.
Covered Shorts Pending Iran Outcome
As noted here last month, in late-February I temporarily covered our shorts pending the outcome of the Iran situation.
I believe this war will inevitably be resolved in our favor, as no matter who runs Iran, it will be militarily defanged and Israel’s air force—with free reign over its skies—will keep it that way, while a consortium will escort ships through Hormuz until it’s safe or Hormuz is bypassed by pipelines.
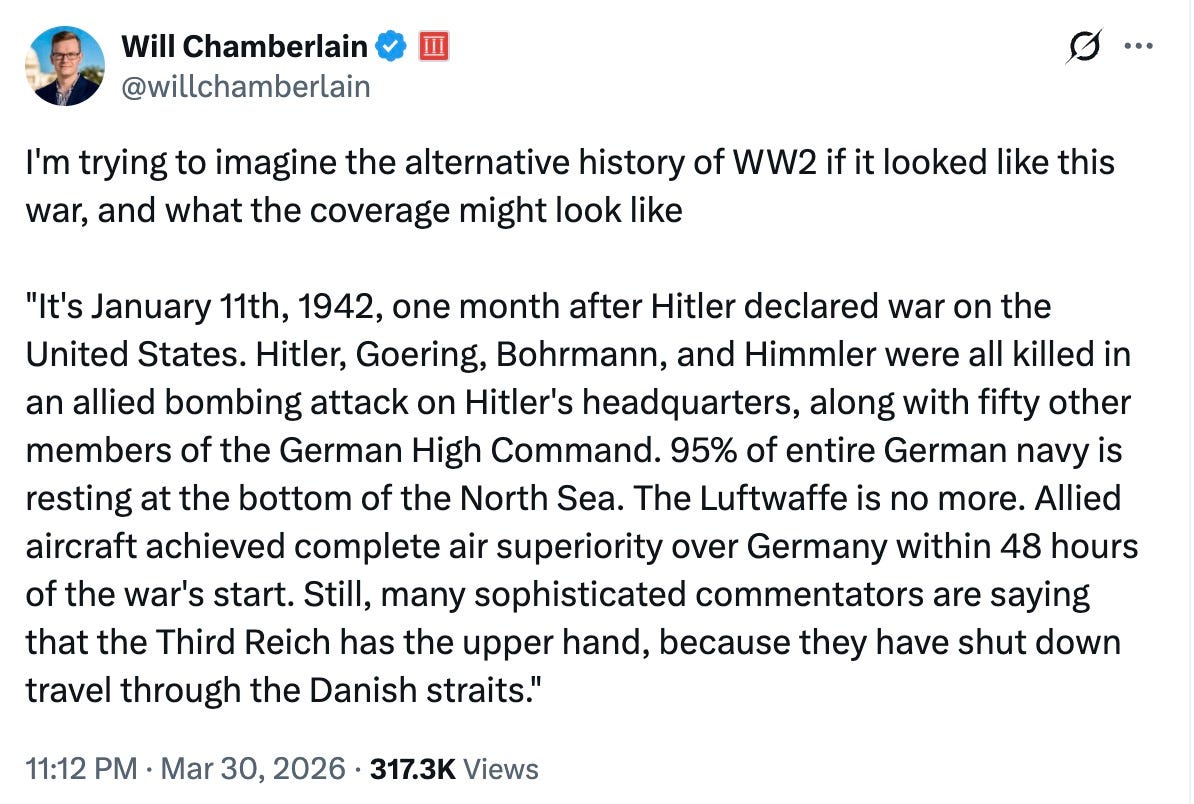
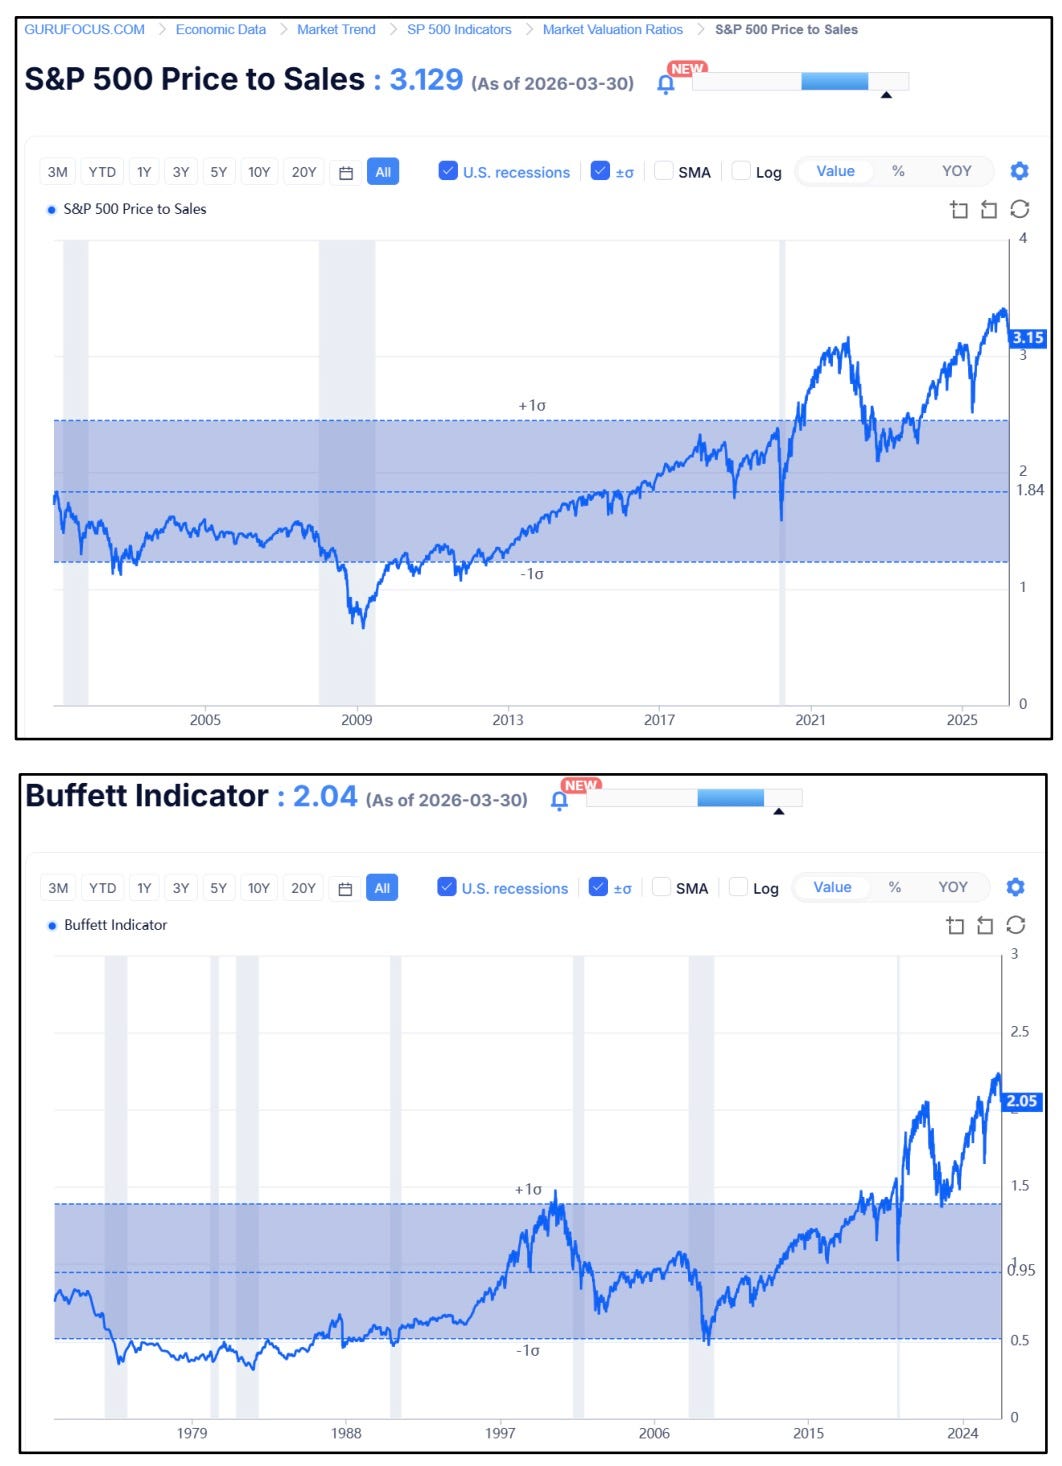
After the stock rally reflecting this plays out, I’ll again be net short this biggest asset bubble in modern history. As I wrote last month, “bubbles find pins,” but I don’t think destroying most of a terrorist state’s military is “a pin.” (The potential implosion of “private credit” may, however, be a different story.)
Now, about that bubble…
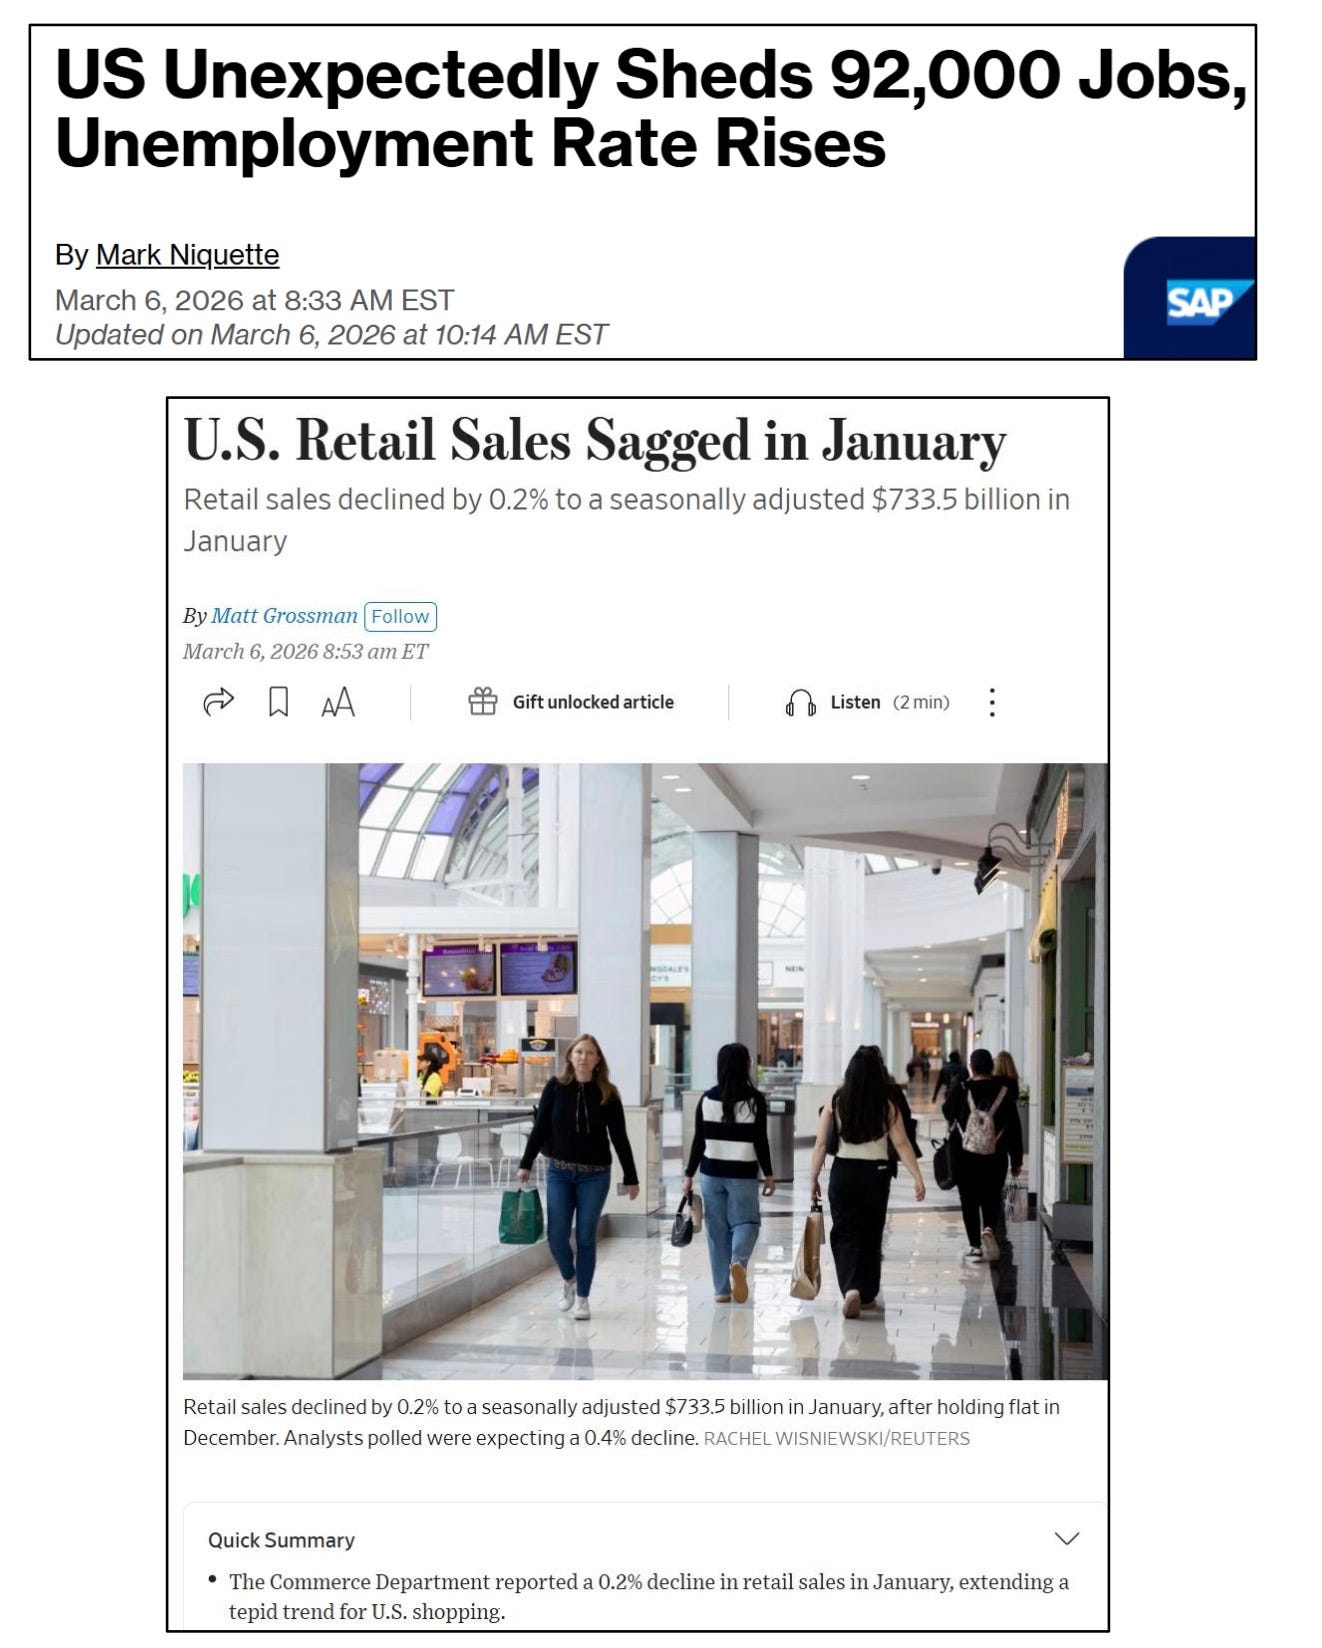
As for the bond market, good luck with this…
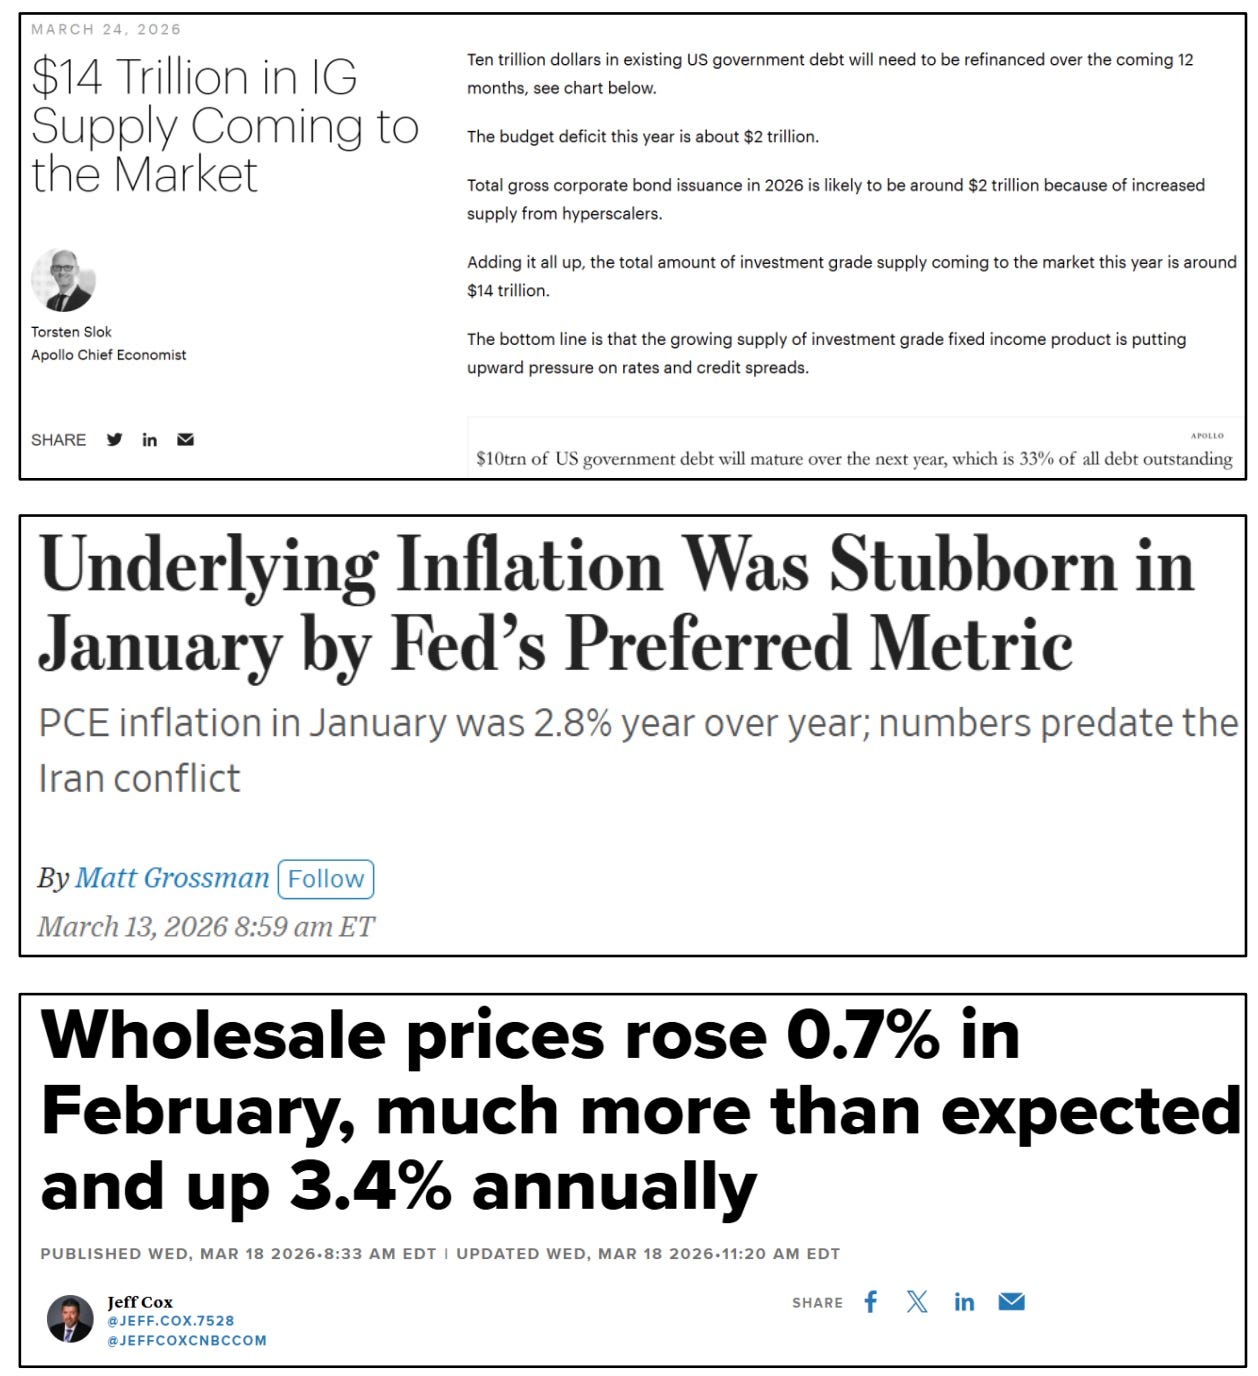
Interest rates clearly won’t be coming down much (if at all) and thus PE multiples need to decline significantly. Factset’s latest estimate for Q1 2026 S&P 500 earnings is $71.24, which is $284.96 annualized. The S&P currently sells for 23x those annualized earnings, yet the traditional “rule of 20” (which says that its PE ratio should be 20 minus the current 2.4% rate of inflation) would put a 17.6x multiple on them, thus bringing that index down to just 5015 vs. the current 6528, a drop of around 23%. However, inflation appears to be accelerating, thereby pressuring that multiple lower.
So, as I wrote at the beginning of this letter, I expect to be short again quite soon, but I think it’s too dangerous to do it until the “Iran discount” is removed.
Now for our long positions…