

Friend of Fringe Finance Lawrence Lepard released his most recent investor letter yesterday. Larry is one of my good friends and favorite financial commentators. I always stop to read this his thoughts, especially on gold, silver, bitcoin and macro.
Larry was kind enough to allow me to share his thoughts heading into Q4 2025. The letter has been edited ever-so-slightly for formatting, grammar and visuals.
In Larry’s letter, he argues we’ve entered a sovereign debt crisis that’s pushing policymakers to run the economy hot, shifting the world from four decades of disinflation to an inflationary regime. He contends debt will be devalued against scarce, non-sovereign money—primarily gold, with bitcoin as a secondary option—citing central bank buying and China’s accumulation. Using gold coverage of the monetary base, he says gold remains undervalued even near $4,000/oz, with long-term averages implying roughly $10,700/oz and panic-era peaks implying up to $30,000/oz. Looking at prior cycles, he considers $8,000/oz plausible in this bull market, especially given how underexposed institutions remain.
He then focuses on miners and bitcoin. Gold and silver miners entered 2025 deeply undervalued and are now catching up as operating leverage boosts margins; an Avino case study shows how production growth and multiple expansion can compound returns. He expects juniors to outperform majors, highlights silver’s record prices and tightening inventories, and views bitcoin as digital gold likely to lag then outrun gold later in the cycle. The team’s stance is to be right and sit tight, with the portfolio tilted to producers (47%), developers (41%), drill stories (4%), and bitcoin/privates (8%), plus a tactical bias toward developers for the next phase.
Part 1 of Larry’s letter was here. This is Part 2.
MONETARY RESET/SOVEREIGN DEBT CRISIS
In past letters, we have discussed the US Debt problem and the mathematical certainty of a “debt doom loop” where spending leads to deficits, deficits lead to debt issuance, debt issuance adds interest expense and that grows the deficit even larger. We have been aware of this issue for several years and it is why we have charted this course for our portfolio. The world has awakened to this reality. Our friend Simon Mikhailovich, who grew up in Soviet Russia and understands monetary chaos, summarized what is occurring in the following Tweet:

The Trump Administration is being forced to “run the economy hot” and focus on growth because of the fiscal mess that they have inherited after 40 years of financial mismanagement by the US Federal Government. With US Federal Debt at 123% of US GDP, and zero will on the part of Congress to control spending, they have no other choice than to emphasize growth.
It is important to understand that what we are witnessing is a sovereign debt crisis, and this has not been seen for over 100 years (with the notable exception of selected third world and developing countries). The last global sovereign debt crisis occurred in the early 1920s as a result of the expenses incurred during WWI and led to hyperinflations in: Germany, Austria, Hungary, Poland, Russia and Greece. It also led to very high inflation in France. Great Britain was forced off the gold standard and devalued the pound, and the US experienced consumer price inflation of 100% in the post war period. as a lot of money was printed to help Europe dig out and to keep the system functioning. Back then it was a war. Today, it is $8T of middle eastern wars, and excess spending on social programs.
That is an important concept to grasp. We are not operating under the normal deflationary conditions that have been present for the past 40 years.
The next chart does a nice job of showing this. We achieved peak deflation in March of 2020. Since then, we have lived in an increasingly inflationary world driven by the fiscal and monetary policies and stimuli that came from the 2008 GFC and the COVID crisis.
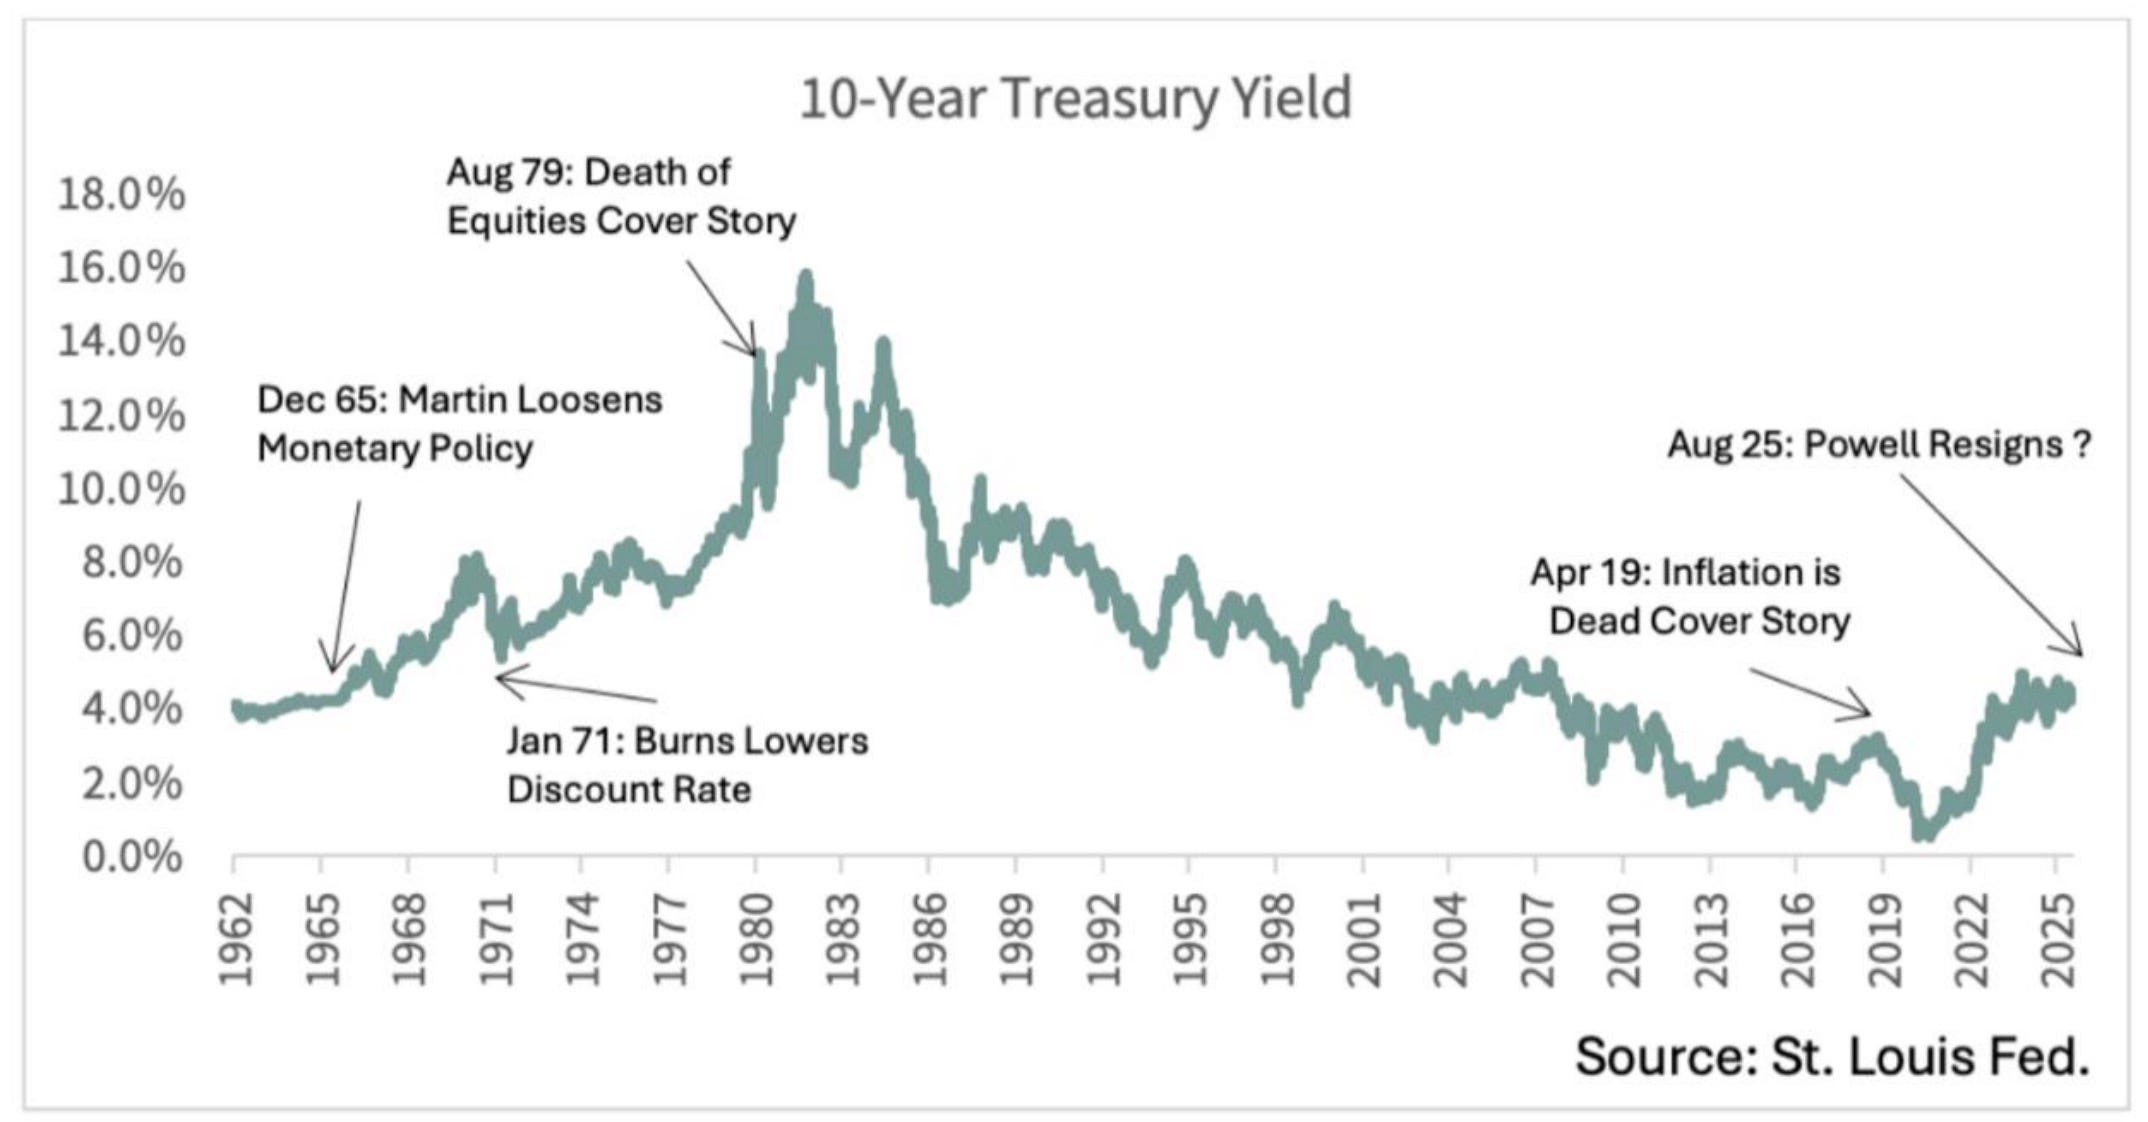
If this is true, and we strongly believe that it is based upon all of the evidence, the best investment strategy is to look at the history books.
The Issue: there is too much debt just like in 1920 and 1945 (post WWI and WWII)
The Solution: inflation is needed to “grow our way out of the debt”; the debt must be devalued against some form of money that is not subject to debasement or excessive money printing.
There are only two choices of non-sovereign counterparty money which are limited in supply against which the debt can be devalued: gold and bitcoin.
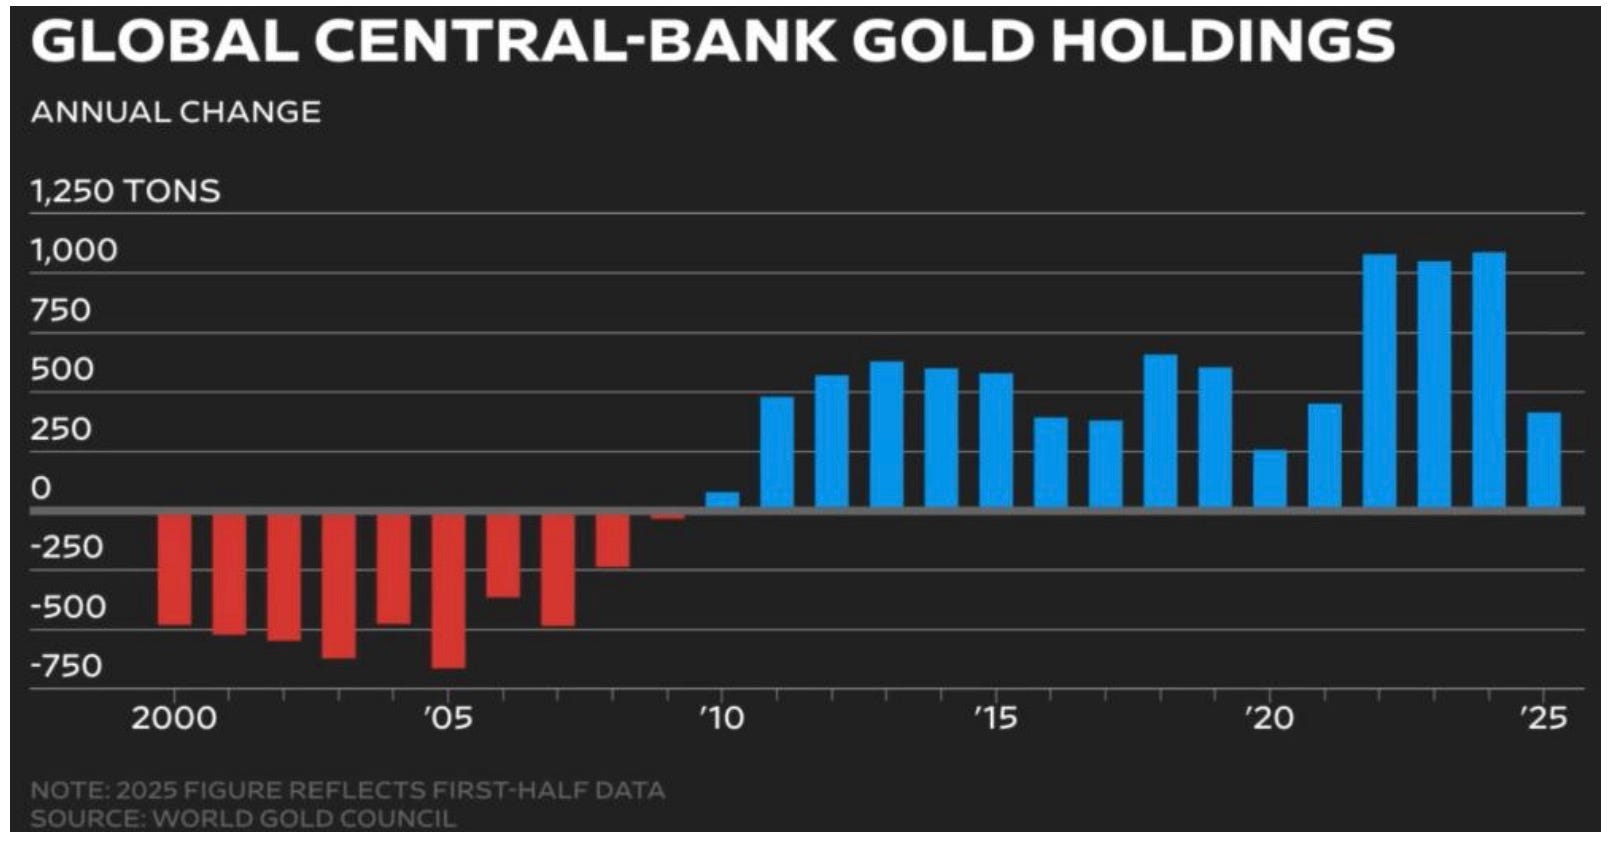
Central Banks worldwide have been enormous buyers of gold over the past several years (chart below) and we have documented this growth in prior letters.
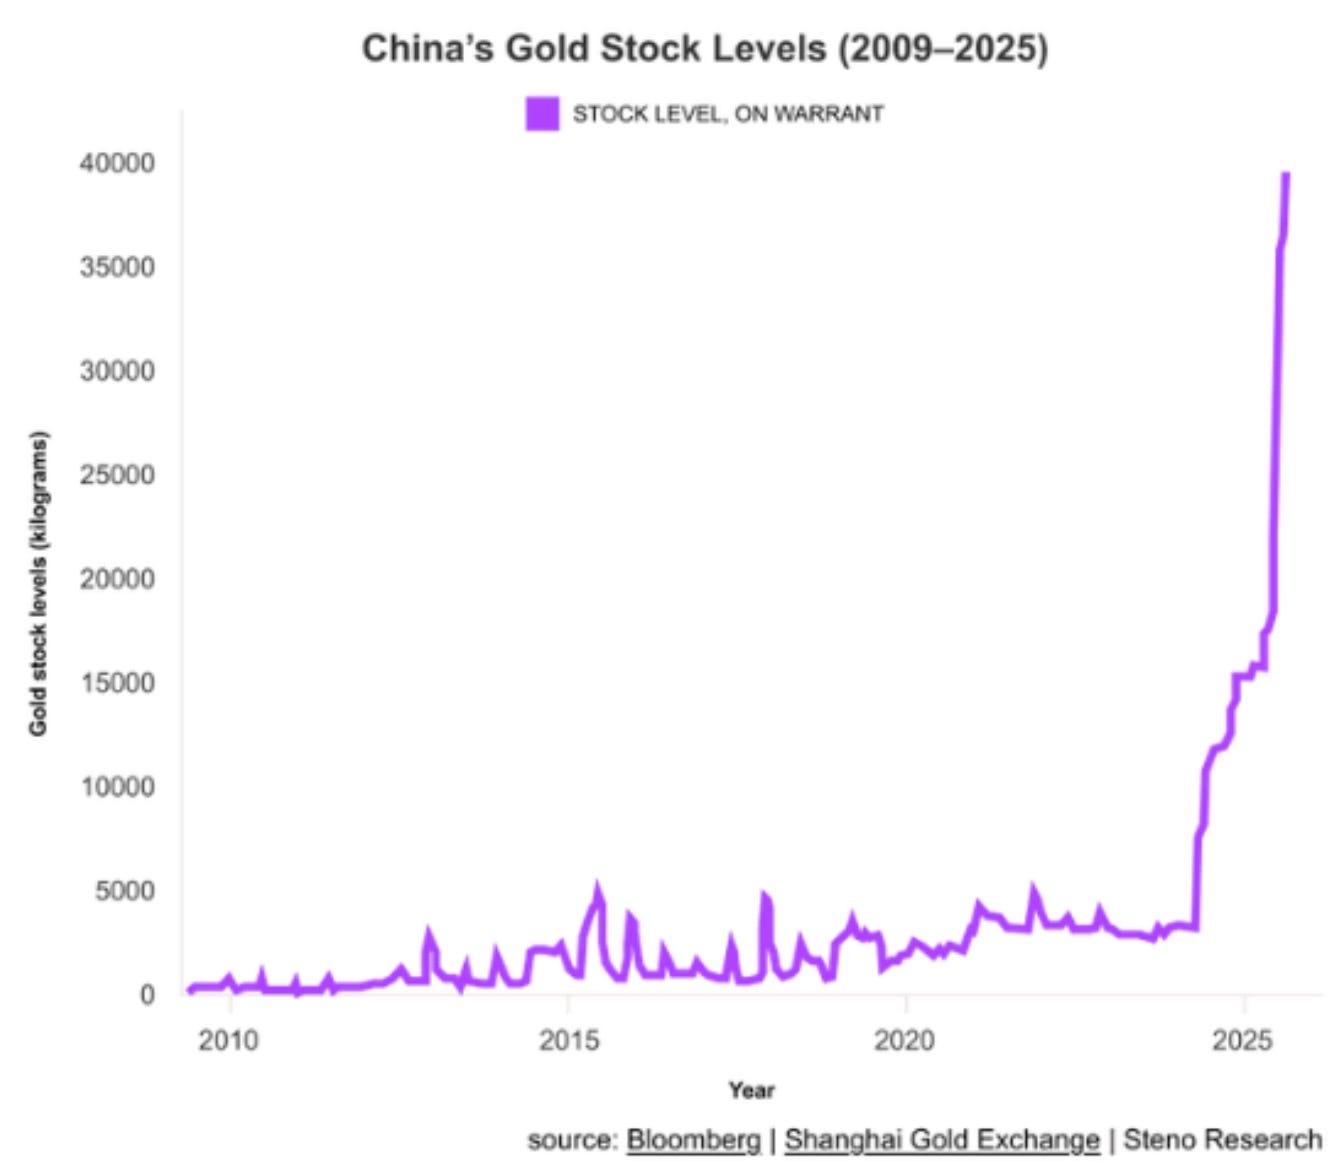
Below is a dramatic chart showing China’s Gold stock levels and how they are accelerating.
Based upon its history, the market depth and tradition we believe that sovereign governments are more likely to attempt a devaluation or reset using gold instead of bitcoin. If this is the case, the mathematics of a reset are extremely interesting and worth considering.