

I’ve long admired Harris Kupperman, the founder of Praetorian Capital, for his ability to cut through noise and spot big-picture themes before they become consensus.
He has a knack for finding opportunities where others aren’t looking, blending a sharp macro perspective with a pragmatic investor’s mindset.

In his latest, he writes about semiconductors. I know my subscribers will benefit from his perspective and wanted to share it with you all this morning.
On Semis
I like to remind people that “when it comes to finance, most things are pretty obvious; it’s the timing that’s hard…”
Through nearly three decades of investing, this concept has constantly proven itself out. Sometimes I really do get it wrong, but usually, I’m just early. As a short, this can be incredibly painful; though as a long, it’s mostly just frustrating to lock up capital that’s going nowhere.
As you can guess, this is the reason I rarely short. That doesn’t stop me from calling balls and strikes. I’ve done this in many prior situations (here and here). Sure, I was often early, but the fever dream eventually broke, and the securities plummeted back to earth. I bring this all up as I’m stupefied by the mania in semiconductors.
To frame this situation, it’s important to remember that semis are incredibly cyclical with multi-year boom and bust cycles. They’re unusually capital intensive as fabs cost billions to assemble, but unlike many other capital-intensive industries, they also face technological obsolescence.
They’re the ultimate sh*tco sector. I literally cannot think of a worse sector to invest in—though I freely admit that every so often, they launch themselves on a super-cycle.
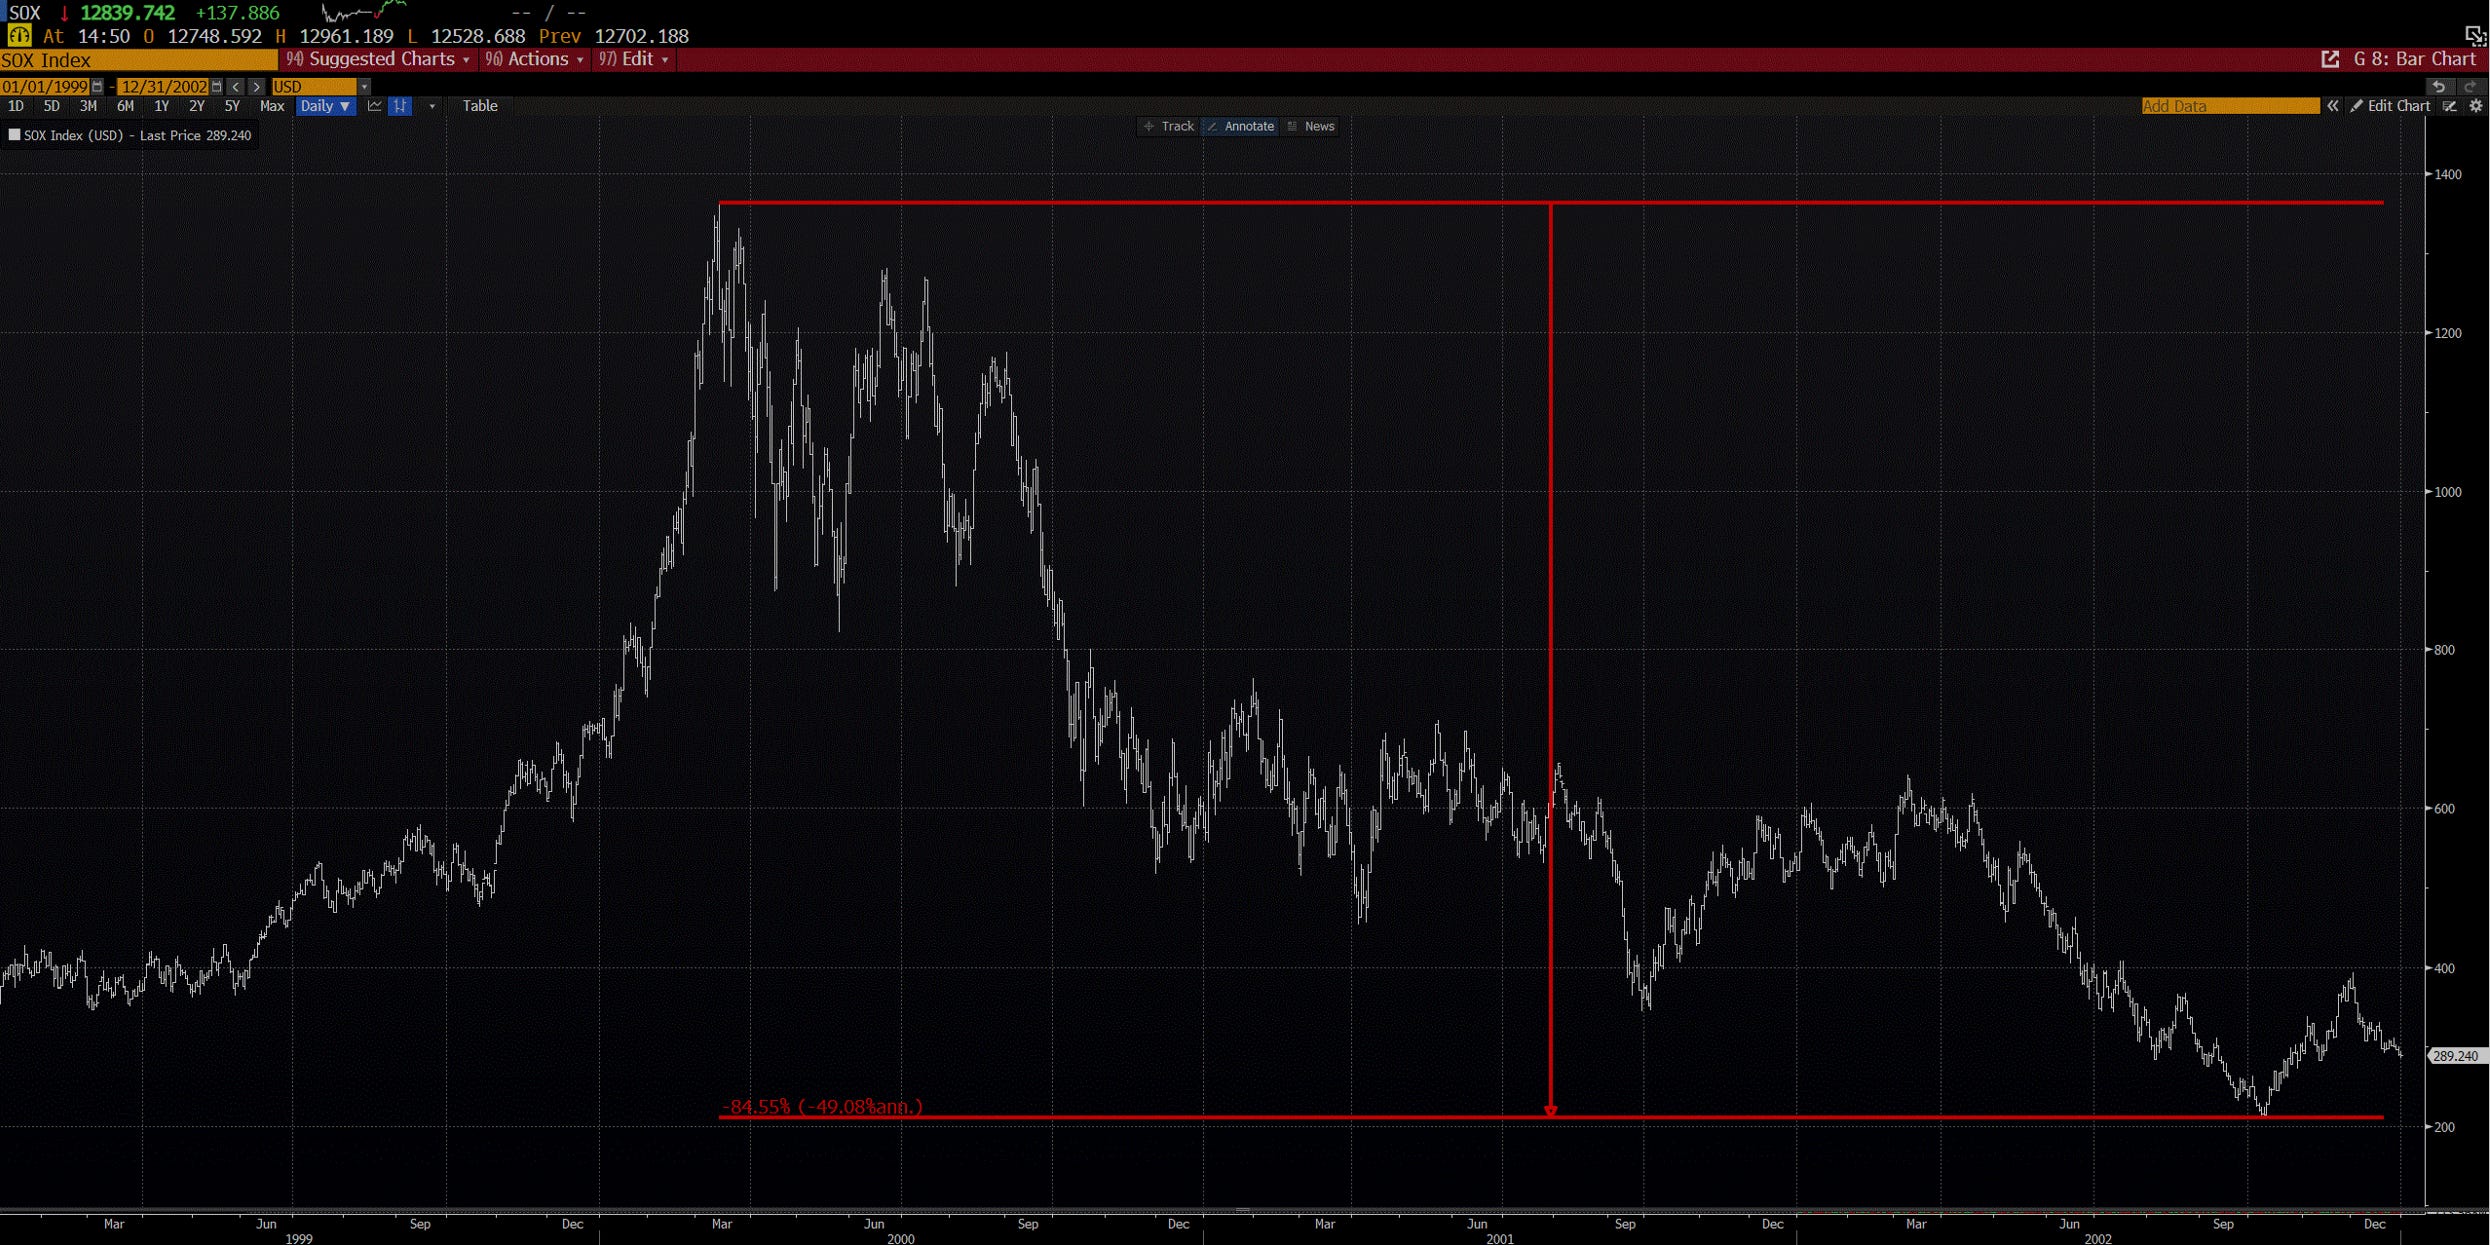
We saw one such super-cycle peak, just as I was coming of age as an investor in 2000. The road down was brutally painful for investors—supply continued ramping as fabs came online; despite orders vaporizing as the tech bubble ended and companies that triple-ordered went bankrupt. At the nadir, which lasted more than a decade, many of the current high-flyers resorted to toxic financings to simply keep the lights on. We’re now into the second such mania of my career.
I get it, AI is hot and you don’t have AI without semis. The buyers seem to be more financially stable than the dot com and fiber players, and the profits are real. Anyone who nailed this on the long side deserves respect. I missed it. However, I also know enough to know that semis are still highly cyclical, and after the peak, there’s likely to be an incredibly painful down-cycle. As a result, everyone invested in semis should be asking themselves a few hard questions: