

Why the hell would anyone own MSTR right now? That is becoming an increasingly difficult question to answer.
MSTR looks to me to have been nothing more than the red-headed stepchild of the Strategy capital structure: the security everyone is willing to sacrifice to make sure everything and everyone else is taken care of. Bitcoin is protected. The preferred securities are supported. The dollar reserve is being built to cover preferred dividends and debt interest.
And when Strategy needs the cash to accomplish all of that, it has repeatedly turned to the same place this year: MSTR shareholders. Hard to find a chart that says “go fuck yourself, shareholders” more than the LTM chart of Strategy. The common is down about -73% in the last year.
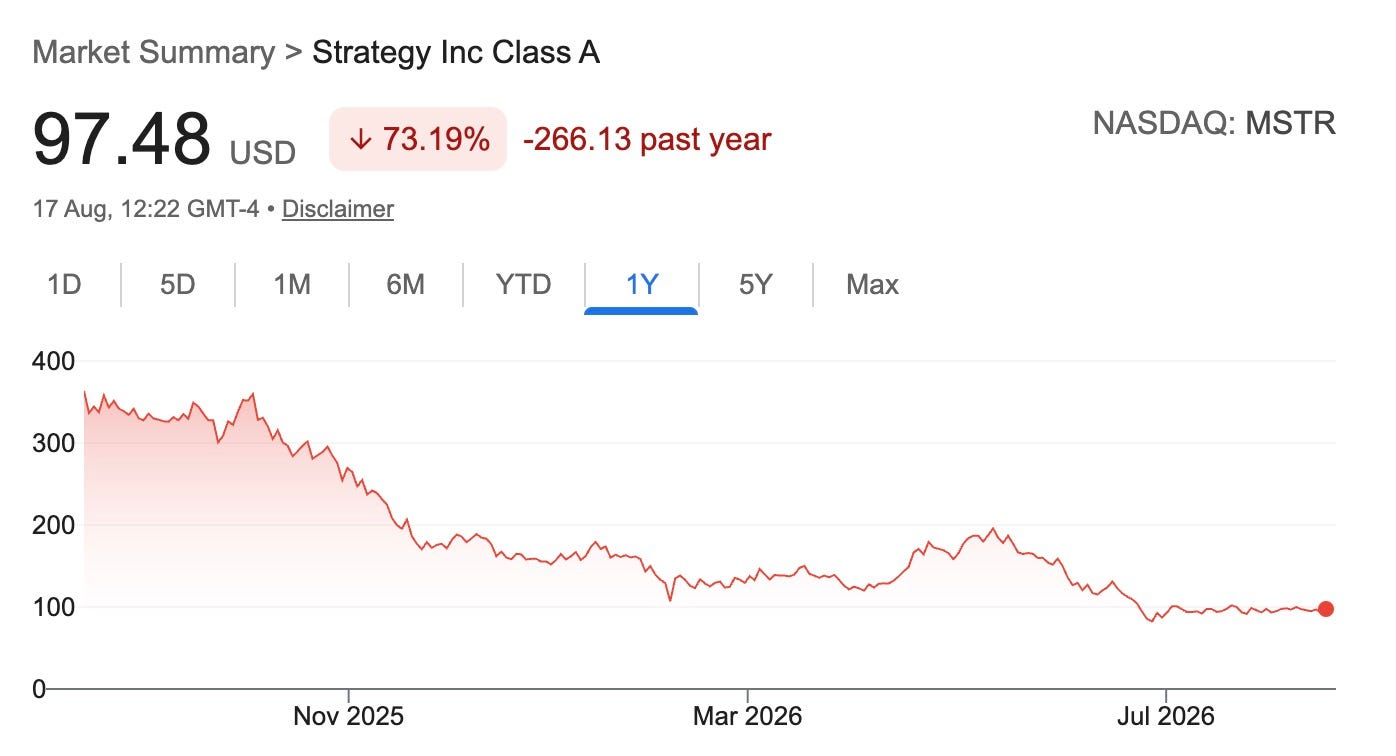
There was always an implicit bargain at the heart of owning Strategy’s common stock. MSTR shareholders accepted extraordinary volatility, leverage, financial engineering and repeated dilution because the prize was supposed to be extraordinary upside to bitcoin. Strategy could issue securities at favorable prices, turn the proceeds into more BTC and potentially allow MSTR to outperform bitcoin itself. Dilution was part of the bargain because the dilution was supposed to make the bitcoin machine more powerful.
But that’s not what much of the recent dilution appears to me to have been about.
Strategy increasingly appears to be operating in defense mode, repeatedly issuing MSTR this year to raise dollars rather than simply using common equity to acquire more bitcoin. The common shareholder is increasingly being used to finance the defenses around the rest of Strategy’s capital structure. And shareholders/investors and observers on Reddit, X and the likes seem to be unamused…
Monday’s disclosure made that reality particularly difficult to ignore. Strategy disclosed that it raised $333.7 million by selling 3.46 million shares of MSTR common stock. It didn’t use that money to buy bitcoin. Strategy instead used $132.2 million to repurchase 1,388,720 shares of STRC, allocated another $52.4 million toward STRC dividends, and added approximately $150 million to its U.S. dollar reserve. Bitcoin holdings didn’t move, leaving Strategy with 840,447 BTC, acquired for roughly $63.36 billion at an average purchase price of $75,385.
This wasn’t an isolated transaction. It fits into a broader series of dilutive common-stock sales this year in which Strategy has increasingly used MSTR as a source of dollars. The company’s USD reserve has now reached approximately $4.8 billion, providing an estimated 2.8 years of coverage for preferred dividends and debt interest. Strategy is effectively building a substantial financial fortress around its bitcoin and the securities sitting above the common stock, and MSTR shareholders are helping pay for it.
From the perspective of Strategy as a corporation, there is an obvious rationale. Preferred shareholders need their dividends, creditors need their interest payments, and confidence in those securities matters if Strategy intends to keep using capital markets to finance its bitcoin strategy. A large dollar reserve gives the company breathing room and reduces the possibility that a prolonged bitcoin downturn could force it to sell BTC.
But what’s good for Strategy isn’t automatically good for MSTR. The uncomfortable reality is that the common stock increasingly looks like the shock absorber for everything else. When Strategy wants more bitcoin, MSTR can be issued. When Strategy wants more dollars, MSTR can be issued. When Strategy wants to strengthen the reserve protecting preferred dividends and debt obligations, MSTR can be issued. And now Strategy has demonstrated that it is willing to sell MSTR while simultaneously using capital to buy back STRC.
Strategy also appears determined not to sell bitcoin. Again, the logic isn’t difficult to understand. Bitcoin isn’t merely an investment portfolio anymore; it is the foundation of the entire Strategy story. If management believes BTC will ultimately be worth multiples of today’s price, selling bitcoin to meet dollar obligations may look like the worst possible source of liquidity. And if it sells, triggering more Bitcoin sales, it could further compromise the business.
So Strategy has another source of capital: its common shareholders. Bitcoin sits at the center and is protected. Preferred securities need to be supported. Debt needs to be serviced. The dollar reserve exists to protect those obligations. Common equity sits underneath all of it, available to be diluted when Strategy needs dollars.
That may be how capital structures normally work, but MSTR isn’t supposed to be a normal common stock. Investors historically paid a substantial premium because they expected amplified participation in Strategy’s bitcoin accumulation machine. Dilution was tolerable when shareholders could see the proceeds flowing directly into additional bitcoin and argue that issuing expensive MSTR shares to buy BTC was ultimately accretive.
Dilution to build a multibillion-dollar cash reserve is different. Dilution to help fund preferred dividends is different. And selling common stock while simultaneously buying back preferred stock is very different. If you own the common, it is becoming difficult to look at those transactions and conclude that your security sits anywhere near the top of Strategy’s list of priorities.
The problem becomes especially serious if bitcoin falls materially from here. Strategy’s dollar obligations don’t disappear when bitcoin declines. Preferred dividends still need to be paid, debt interest still exists and the company still needs liquidity. Meanwhile, falling bitcoin would likely pressure MSTR, meaning every dollar subsequently raised through common-stock issuance would require selling more shares.
That could create an ugly dynamic. The lower MSTR goes, the more painful raising a fixed amount of cash becomes for existing shareholders. If Strategy remains deeply reluctant to sell bitcoin, common equity remains one of the most obvious sources of liquidity. The $4.8 billion reserve reduces the immediate risk, but shareholders should recognize the trade-off: Strategy has made the corporation safer partly by diluting MSTR. The reserve protects Strategy from being forced to sell bitcoin. It doesn’t necessarily protect the value of each MSTR share.
And the upside scenario isn’t as attractive as it once looked either. If bitcoin rallies sharply, MSTR should benefit enormously. Strategy owns 840,447 BTC, so a major bitcoin bull market obviously matters to the common stock. But shareholders still have to ask how much greater their participation in that upside might have been without all the dilution.
Every new common share expands the denominator. Dilution can create shareholder value when shares are issued at attractive valuations and the proceeds are deployed into assets that increase value per share. That was always central to the Strategy thesis. But issuing MSTR to accumulate BTC and issuing MSTR to accumulate dollars are not economically identical. Issuing MSTR while spending capital to retire STRC makes the distinction even harder to ignore.
The result is an increasingly unattractive asymmetry. If bitcoin falls, MSTR shareholders potentially absorb enormous downside. If bitcoin rises, they participate in the upside through a larger share count. Bitcoin can rally, Strategy’s holdings can become dramatically more valuable and MSTR can rise substantially, while shareholders can still reasonably conclude they would have captured more of that upside without the dilution used to finance cash reserves, preferred dividends and preferred-stock repurchases.
Monday’s disclosure crystallized the problem. Strategy raised $333.7 million by selling MSTR and then spent $132.2 million buying back STRC. Whatever the corporate rationale, the message to the common shareholder is difficult to miss: Strategy was willing to increase the supply of your security while reducing the supply of another security sitting above you.
The original bull case for MSTR was never simply that bitcoin would go up. If that were the thesis, investors could just buy bitcoin. MSTR’s appeal was that Strategy could exploit its access to capital markets to create something more powerful: a vehicle capable of repeatedly raising capital and converting it into increasing bitcoin exposure. The magic wasn’t merely owning BTC; it was combining bitcoin, leverage, capital-market access and accretive issuance in a way that potentially gave common shareholders something they couldn’t replicate by holding bitcoin themselves.
That proposition now looks much less straightforward. Building a massive cash reserve may prove smart. Supporting STRC may preserve access to an important financing market. Refusing to sell bitcoin may ultimately prove enormously valuable. But all of those things can be good for Strategy while imposing a meaningful cost on existing MSTR holders.
There is still a bullish case. Strategy’s enormous bitcoin position could eventually overwhelm concerns about dilution, and today’s defensive moves could help the company survive long enough to exploit another major bitcoin bull market. MSTR could ultimately trade far above where it does today.
But that’s no longer enough to avoid the basic question. If you’re bullish on bitcoin, you can own bitcoin. If you want a Strategy preferred security, there are now multiple choices designed to receive distributions and sit above the common stock. And if you own MSTR, you own the piece of the capital structure that Strategy has repeatedly demonstrated it is willing to dilute to protect everything else.
Bitcoin is the asset Strategy doesn’t want to sell. The preferred securities are obligations it wants to support. The dollar reserve is protection it wants to build. Those priorities may make perfect sense for Strategy as an enterprise, but somebody has to provide the capital that allows the company to protect them.
Increasingly, that somebody is the MSTR shareholder. Which brings us back to the simplest questions of all:
Why would anyone own MSTR right now?
What is going to happen to MSTR (and even STRC) the next time Strategy adds even more to the capital structure on the way up and Bitcoin crashes again, maybe even for good?

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author. I cannot guarantee the accuracy of all facts and figures included in this article though I made my best effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
As of May 20, 2026 I am attempting to no longer actively trade as much as I once did (read my story here). My eventual goal is for investing/saving to be mostly done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. Basically, via index funds, ETFs and individual equities it is possible I could own, have exposure to, or not own anything at any point. As of the same date, May 20, 2026, in an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
And all positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
Thank you. I've been saying this for a year. I've been long STRC for months. Had I been smart, I would also have been short MSTR.
"If you own the common, it is becoming difficult to look at those transactions and conclude that your security sits anywhere near the top of Strategy’s list of priorities."
This is the issue that is most surprising to me. In Capital Markets 101, investors are supposed to learn that there is a capital stack: Bonds sit at the top, then preferred stock, then common stock. While Strategy has introduced many clever variants, the basic rules are still intact.
STRC was a great buy at $71.5. It is tied for the second senior-most claim on Strategy's assets. But, for that same reason, MSTR was a terrible play with BTC sitting between $55,000-$60,000 and Strategy's average BTC acquisition cost at $75,000.
Capital markets are efficient in the long term, but occasionally they can be very stupid in the short term.
Painful being a common shareholder recently but to be clear it 100% depends on your entry price and implied MNAV at time of purchase. If you look at slide 14 of the Q2 26 Earnings Pres can see a demonstrated history of growth in SATS per share year over year (56k/share in 2020 to 203k/share as of 7/26/26). If BTC is down 50% from ATH it makes complete sense that as an intelligently levered BTC play the common would be down by an amplified amount. Accordingly when the market turns bullish the stock would be expected to outperform BTC.
So to answer your question Quoth - investors that believe in the longer term BTC thesis being intact and have a desire to seek amplified returns (w accepted amplified volatility) should buy the stock at these levels. There may also be institutional holders that have a mandate to own common stocks and are not allowed to invest in commodities / digital assets that would like to express a view on BTC so logical for them to own it.
TLDR as in any asset the purchase price (implied multiple) matters and zooming in on a couple month trend of active capital management to craft a long term narrative is flawed IMO. In a bull run on BTC all the excess returns over and above their debt / pref obligations flow straight to the common shareholders (Amplification!). Not to mention as the collateral value and credit coverage ratios improve, the ability to issue more STRC and tighten the dividend will just add reflexivity to the common via increased SATS per share. Defense for bear markets and offence for Bull markets....